
 Basiran
In the modern landscape of high-stakes personal finance, the role of the primary provider is often romanticized as one of stoic strength. However, the reality behind the spreadsheet is frequently a narrative of hidden burdens, quiet calculations, and the heavy toll that fiscal volatility takes on personal relationships. For many, the "provider’s paradox"—the desire to build a secure future while simultaneously fearing that the pursuit of that security is sabotaging the present—is a constant, gnawing reality.
This tension recently came to a head for one family, whose planned getaway to Las Vegas served as a backdrop for a much larger, internal reckoning regarding money, stress, and the unintended consequences of shielding loved ones from the realities of financial management.
The Chronology of a Crisis: From Planning to Pivot
The conflict began with an innocuous suggestion. A few days before the publication of a personal finance piece titled Broke Again At 49, the author proposed a long-weekend trip to Las Vegas. His wife, taking the initiative to ensure the family could enjoy a high-quality experience, spent hours curating a logistical masterpiece: flight itineraries, hotel bookings, and a schedule of entertainment—all with the intent of securing better rates and premium seats.
However, in the nine days between the suggestion and the finalization of the plan, the financial climate shifted dramatically. A $25,000 capital call from a venture fund landed on the author’s desk. In the world of private equity and venture capital, "when it rains, it pours," and this unexpected outflow threatened to derail the liquidity required for the trip.
When presented with the $6,000–$7,000 price tag, the author’s response was not the enthusiastic approval his wife had earned, but a cold, "let me get back to you." The resulting tension was palpable. She had done the heavy lifting of planning, only to be met with hesitation from the very person who had initiated the idea. Because the author had stopped sharing his editorial drafts with his spouse—a side effect of the rise of AI tools in his workflow—she remained unaware of the deeper financial context driving his sudden pivot toward austerity.
The Uncomfortable Position of the Provider
Every father, and indeed every primary provider, operates under a self-imposed mandate to deliver the "best life possible." When that mandate is threatened by market forces or poor forecasting, the emotional sting is immediate.
The author faced a stark dilemma: cancel the trip to prioritize liquidity, or move forward and shoulder the stress of the expense. To his credit, his spouse was willing to pivot to a staycation, acknowledging that the household needed to remain agile. However, after a week of intensive financial "manifesting"—an exercise in reallocating assets to ensure liquidity for future capital calls—the author decided to proceed. He recognized that he had miscalculated his own risk; he had anticipated a 30% capital call over 12 months, but reality had delivered 46% in just six.
"I wasn’t going to make my family pay for my bad forecasting," the author noted. The decision was made to treat the trip as a non-negotiable expense, effectively decoupling his financial blunders from his family’s right to enjoy their time together.
The Psychology of the "Nothing-Burger"
Despite the decision to proceed, the stress did not dissipate; it simply mutated. During the trip, the author found himself plagued by the "silent burden" of the provider. While playing poker at a local casino, he suffered a $350 loss in a "bomb pot." Though a standard occurrence for a gambler, the loss served as a catalyst for a heightened state of irritability.

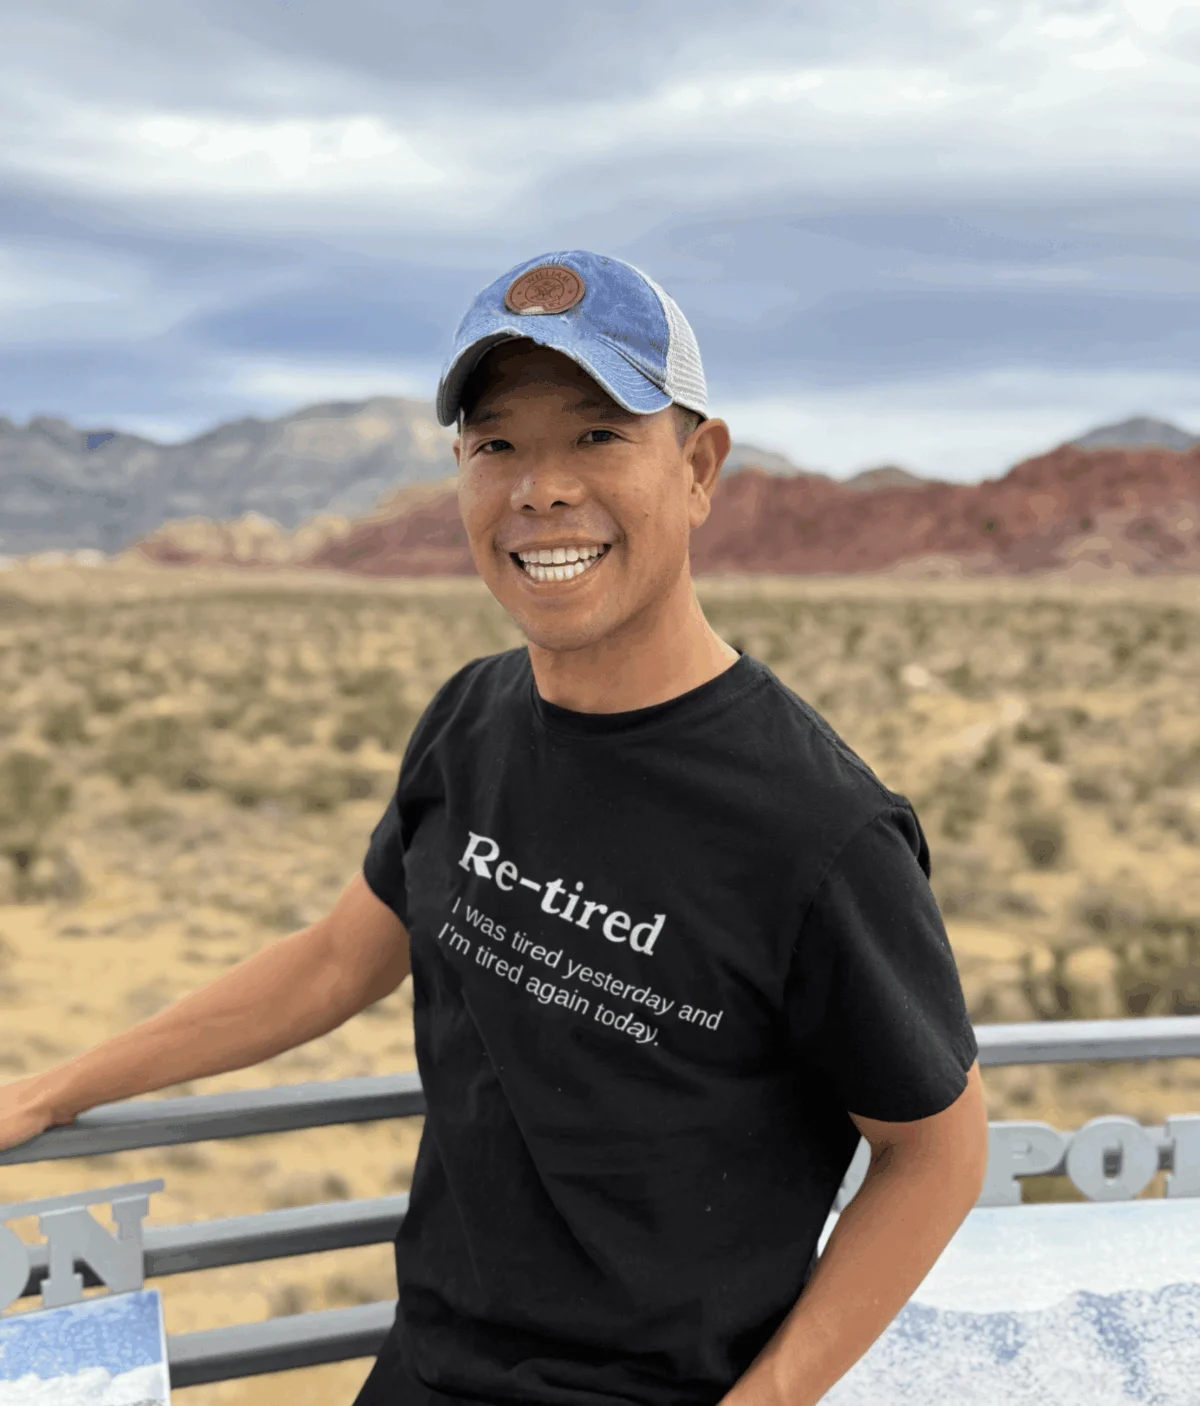
This manifested most clearly at Red Rocks, where the author requested a series of portrait photographs. Under the weight of sleep deprivation—having slept only four hours—and the lingering anxiety of the venture fund obligations, he began to provide the sort of granular, critical feedback typically reserved for a professional studio session. He asked for specific angles and vertical framing, inadvertently projecting his stress onto his wife.
What should have been a simple request became a flashpoint for conflict. To the wife, the instructions felt like a critique; to the husband, the perceived irritation of his wife felt like a rejection. It was a classic "nothing-burger" that escalated into a significant emotional rift. It is a common phenomenon: when a provider carries the weight of financial uncertainty in silence, their emotional bandwidth for everyday interactions shrinks. A sigh, a brief pause, or a neutral expression is easily misread as a verdict on their worth.
Implications for Financial Stability and Relationships
The lessons derived from this experience are threefold, offering a roadmap for others in high-pressure financial positions.
1. The Necessity of the Cash Buffer
The most immediate takeaway is the re-evaluation of liquidity. The author concluded that a six-month cash buffer is non-negotiable. While the opportunity cost of holding cash has historically been viewed as a drag on portfolio performance, in the current high-yield interest rate environment, cash is "emotional capital." It provides the freedom to say "yes" to life experiences without the paralyzing fear of impending financial obligation.
2. The Trap of Hyper-Optimization
"Recovering optimizers" often fall into the trap of squeezing every dollar of value out of a transaction. While saving $1,000 by cutting a day from a trip is mathematically sound, the psychological cost—the "mental tallying" of expenses during the vacation—effectively ruins the return on investment. The author realized that the marginal benefit of that $1,000 was far outweighed by the cost to his presence and emotional engagement with his children.
3. The Danger of Silent Stoicism
The most profound implication is the danger of the "lone wolf" provider. Men, in particular, are conditioned to bury feelings of fear or inadequacy. However, as the author realized, stress is not static; it leaks. It manifests as irritability and distance. The antidote is radical transparency—not necessarily sharing every granular detail of a portfolio, but acknowledging the state of the household’s emotional and financial health. "I am feeling stretched right now" is a powerful sentence that sets expectations and prevents the partner from guessing—and, crucially, guessing wrong.
Conclusion: Investing in the Present
Ultimately, the goal of investing is to provide for the future, but the goal of life is to inhabit the present. When a financial provider allows a capital call or a bad poker hand to overshadow a family’s joy at a landmark like Red Rocks, they have failed to balance their portfolio of responsibilities.
Forced change, often viewed as a negative, is frequently the greatest catalyst for personal growth. The author’s realization that he had been "optimizing" his way into misery is a stark reminder to all providers: the portfolio is only as healthy as the person managing it. By shifting from a mindset of constant defense to one of intentional presence, the provider can ensure that the "green" of their financial accounts does not come at the expense of the "red" in their personal happiness.
As the author put it, "Any investor knows not to let one red position ruin a green portfolio." Moving forward, the focus shifts from the accumulation of capital to the preservation of the experiences that make that capital worth earning in the first place.

 Iffa Jayyana
 Asro

 Raul Delapena Setiawan

 Dwi Wanna

 Muslim

 Nana Wu


 Rifan Muazin
