
 Sagoh
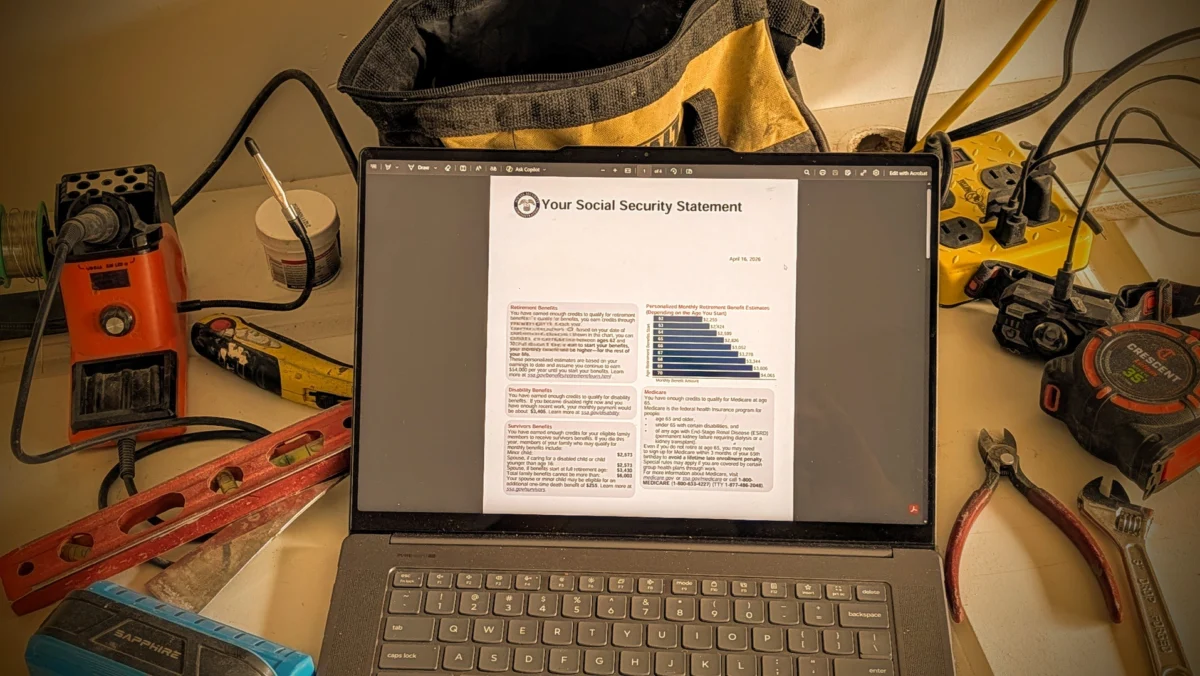
For decades, the FIRE (Financial Independence, Retire Early) movement has been defined by its singular focus on the "stash"—the private investment portfolio that allows individuals to exit the workforce in their 30s or 40s. In this pursuit, Social Security is often dismissed as a "fuzzy concept," a distant government promise that, for the ambitious early retiree, feels like a rounding error in a lifetime of aggressive saving.
However, as the pioneers of the FIRE movement transition into their middle years, a shift in perspective is occurring. What was once considered an irrelevant benefit is now being recognized as a sophisticated tool for optimizing retirement strategy. By applying the financial principle of Net Present Value (NPV), retirees can transform Social Security from a hypothetical future check into a concrete, present-day asset that bridges the gap between early exit and financial security.
The Evolution of the FIRE Mindset
In 2005, the concept of early retirement was largely a battle against the status quo—saving aggressively, cutting costs, and building a self-sustaining engine of capital. During this era, Social Security was sidelined. It was perceived as a safety net for those who lacked private savings, not a foundation for those who had already achieved independence.

Yet, time is the great equalizer. As early retirees enter their 50s and 60s, the "distant future" begins to materialize. The realization has dawned that Social Security is not merely a government entitlement; it is a guaranteed, inflation-adjusted annuity. When viewed through the lens of actuarial math, it represents a substantial addition to one’s net worth—one that many people have been leaving out of their spreadsheets entirely.
Understanding the Math: Net Present Value
To properly incorporate Social Security into a retirement plan, one must move past the nominal monthly payout and consider its Net Present Value. In financial terms, NPV calculates the current value of a stream of future payments, adjusted for the time value of money.
For a 30-year-old, the NPV of Social Security is effectively negligible. The compounding power of their own investments over three decades far outweighs the discounted value of a future benefit. However, for a 55-year-old or a 60-year-old, the math shifts dramatically. If you have a low cost of living, Social Security could theoretically cover all your basic needs, turning your entire existing portfolio into a "play money" or "legacy" fund.

The Calculation Methodology
The formula for NPV is complex, but in the digital age, it is highly accessible. By using standard financial calculators or AI-driven analytical tools, one can input their estimated monthly benefit, the years until eligibility, and an assumed discount rate (the rate of return one would expect from an investment of similar risk).
For instance, consider a 30-year-old couple aiming for a $4,000 monthly benefit starting at age 62. If they were to save for that income stream today, they would need a massive capital base. When you account for 32 years of growth, that future benefit has an NPV of approximately $98,000. This is not just a theoretical number; it is an equivalent asset that can effectively reduce the amount of capital one needs to save today.
Chronology of Benefit Eligibility
Understanding the mechanics of the Social Security Administration (SSA) is crucial for anyone planning their "liftoff" date. The system is designed with specific milestones:

- Early Eligibility (Age 62): This is the earliest point at which benefits can be drawn. While the monthly amount is permanently reduced compared to the "Full Retirement Age," it provides immediate liquidity.
- Full Retirement Age (Age 67 for those born in 1960 or later): This is the threshold where the government pays 100% of the calculated benefit.
- Delayed Retirement Credits (Up to Age 70): For every year one waits past the Full Retirement Age, the benefit increases by approximately 8%.
The common advice from legacy financial planners is to "tough it out" until 70 to maximize the payout. However, for the FIRE-minded individual, this advice often fails to account for the opportunity cost of working.
The Case Study: "Shane Survivor" at 55
Consider the scenario of "Shane," a 55-year-old who experienced a business failure and is looking to retire immediately. Traditional advisors might suggest he work until 67 or 70 to maximize his Social Security. But when we calculate the NPV, we find a counterintuitive reality: working longer for a higher check may not be the optimal path.
If Shane begins taking benefits at 62, he can start investing those payments immediately. A 6% annual return on those early payments creates a "snowball effect" that often outpaces the incremental increases he would receive by waiting until 67. When Shane realizes that he doesn’t need to reach the "maximum" benefit to achieve his lifestyle goals, he gains the freedom to exit the workforce years earlier than he ever thought possible.

Official Perspectives and Policy Risks
Critics of this strategy often point to the potential for Social Security reform. It is a common refrain: "What if the program is canceled?"
From a policy standpoint, Social Security remains the most politically sensitive program in the United States. Given that the demographic shift toward an aging population makes retirees a powerful voting bloc, drastic cuts are highly unlikely. What is more probable—and indeed, already occurring—is a "means-testing" approach. Benefits may be reduced for high-income earners. Ironically, for the successful FIRE retiree, this is a non-issue; if you have enough in your private portfolio to weather a reduction in Social Security, the government’s policy changes become a matter of political observation rather than a personal financial crisis.
Implications for Future Planning
The shift in viewing Social Security as an asset class rather than an afterthought has three primary implications for the retirement planning industry:

1. The "Safety Margin" Effect
By acknowledging the NPV of your future benefits, you create a "safety margin." This reduces the psychological pressure to reach an arbitrary, often inflated "FI number" (the total amount needed to retire). If your portfolio is $100,000 short of your target, but your future Social Security has an NPV of $200,000, you have essentially already met your goal.
2. The Incentive to "Slack"
Because Social Security is calculated based on an average of your highest 35 years of earnings, the system is inherently progressive. It provides a disproportionate benefit to those who have shorter, high-earning careers compared to those who work for 45 years. This provides an unintentional, yet powerful, incentive for early retirement. The "cost" of retiring early in terms of lost Social Security is lower than most people assume.
3. Leveraging AI for Personalized Projections
The complexity of Social Security—with its varying tax treatments, spousal benefits, and earnings tests—often leads to "analysis paralysis." Today’s tools, including advanced LLMs (Large Language Models), allow users to run thousands of scenarios in seconds. By inputting their specific earnings history from SSA.gov, individuals can now model the exact impact of retiring at 50, 55, or 60.

Conclusion: A New Era of Financial Security
The journey to financial independence is no longer just about the accumulation of private assets. It is about the holistic management of all available resources. By integrating Social Security into the broader retirement strategy, the FIRE movement is maturing.
The goal is not to rely on the government, but to use the government’s own structure to provide a floor for one’s financial life. As you look at your own path, remember that the numbers are more flexible than they appear. The "stash" is not just the stocks and bonds in your brokerage account—it is the sum of your current capital, your ability to earn, and the invisible, yet powerful, promise of a future income stream waiting at the end of the road.
Your Homework: If you haven’t yet, visit SSA.gov and create your account. Run your numbers, look at your projected benefits, and calculate your Net Present Value. You may find that you are much closer to the finish line than you ever dared to believe.

 Muslim
 Rifan Muazin

 Ammar Sabilarrohman

 Asep Darmawan

 Asro

 Layla Zulfa

 Nila Kartika Wati

