
 Rifan Muazin
For many, the role of a primary provider is synonymous with stability, foresight, and unshakeable calm. However, behind the closed doors of many households, the reality is far more nuanced. It is a world of "silent burdens"—where the weight of investment obligations, market volatility, and long-term planning can manifest as sudden, uncharacteristic irritability. This is the story of a recent family excursion to Las Vegas that serves as a case study for the psychological toll of financial stewardship and the necessity of recalibrating one’s relationship with money.
The Trigger: When Life Intersects with Capital Calls
The narrative begins with a classic domestic scenario: a family trip to Las Vegas. The author, having floated the idea of a long-weekend getaway to his wife, expected a standard planning process. However, his spouse took the initiative, spending hours researching flights, hotel accommodations, and entertainment. With only nine days until the trip, the logistics were complex, complicated by the specific needs of two children, including food allergies and sleep sensitivities.
The projected cost for the trip ranged between $6,000 and $7,000. Under normal circumstances, this would have been a welcomed development. Yet, in the interim between the initial suggestion and the final planning, the author was hit with a $25,000 capital call from a venture fund.
In the world of high-stakes personal finance, "when it rains, it pours." This unexpected obligation created an immediate conflict. Faced with a choice between canceling the trip to prioritize liquidity or moving forward despite the financial strain, the author found himself in a state of paralysis. He told his wife he needed to "think about it"—a response that, while fiscally responsible, lacked the enthusiasm his partner’s hard work deserved. This friction highlights a pervasive issue among providers: the tendency to withhold information to "protect" family members, which ultimately creates a barrier of misunderstanding.
Chronology of the Trip: A Study in Managed Expectations
The days leading up to the departure were defined by a rigorous attempt to rectify the balance sheet. After engaging in a personal financial "manifesting" exercise and securing enough liquidity to cover future obligations for the next three to six months, the author felt the weight of the pressure subside.
The decision to proceed was rooted in a sense of accountability. The author had previously forecasted a 30% capital call rate over 12 months, yet 46% had been called in just six. Acknowledging that this was his error in forecasting, he refused to allow his family to pay the price for his professional miscalculation. They reached a compromise: a three-night stay instead of four, effectively trimming the budget by approximately $1,500.
The itinerary was meticulously curated. They stayed at the Palazzo, booking two adjoining rooms to ensure comfort. The schedule included high-quality entertainment—Blue Man Group, Cirque du Soleil, and the Popovich Comedy Pet Theater—with an average ticket cost of $450 to $500 for the family. The trip also featured cultural enrichment at the Illusions Museum, the Flyover, and a scenic excursion to Red Rocks. Dining, while indulgent, served as a nod to the author’s professional past at Smith & Wollensky, adding a layer of nostalgia to the experience.
The Tipping Point: A Micro-Moment of Misalignment
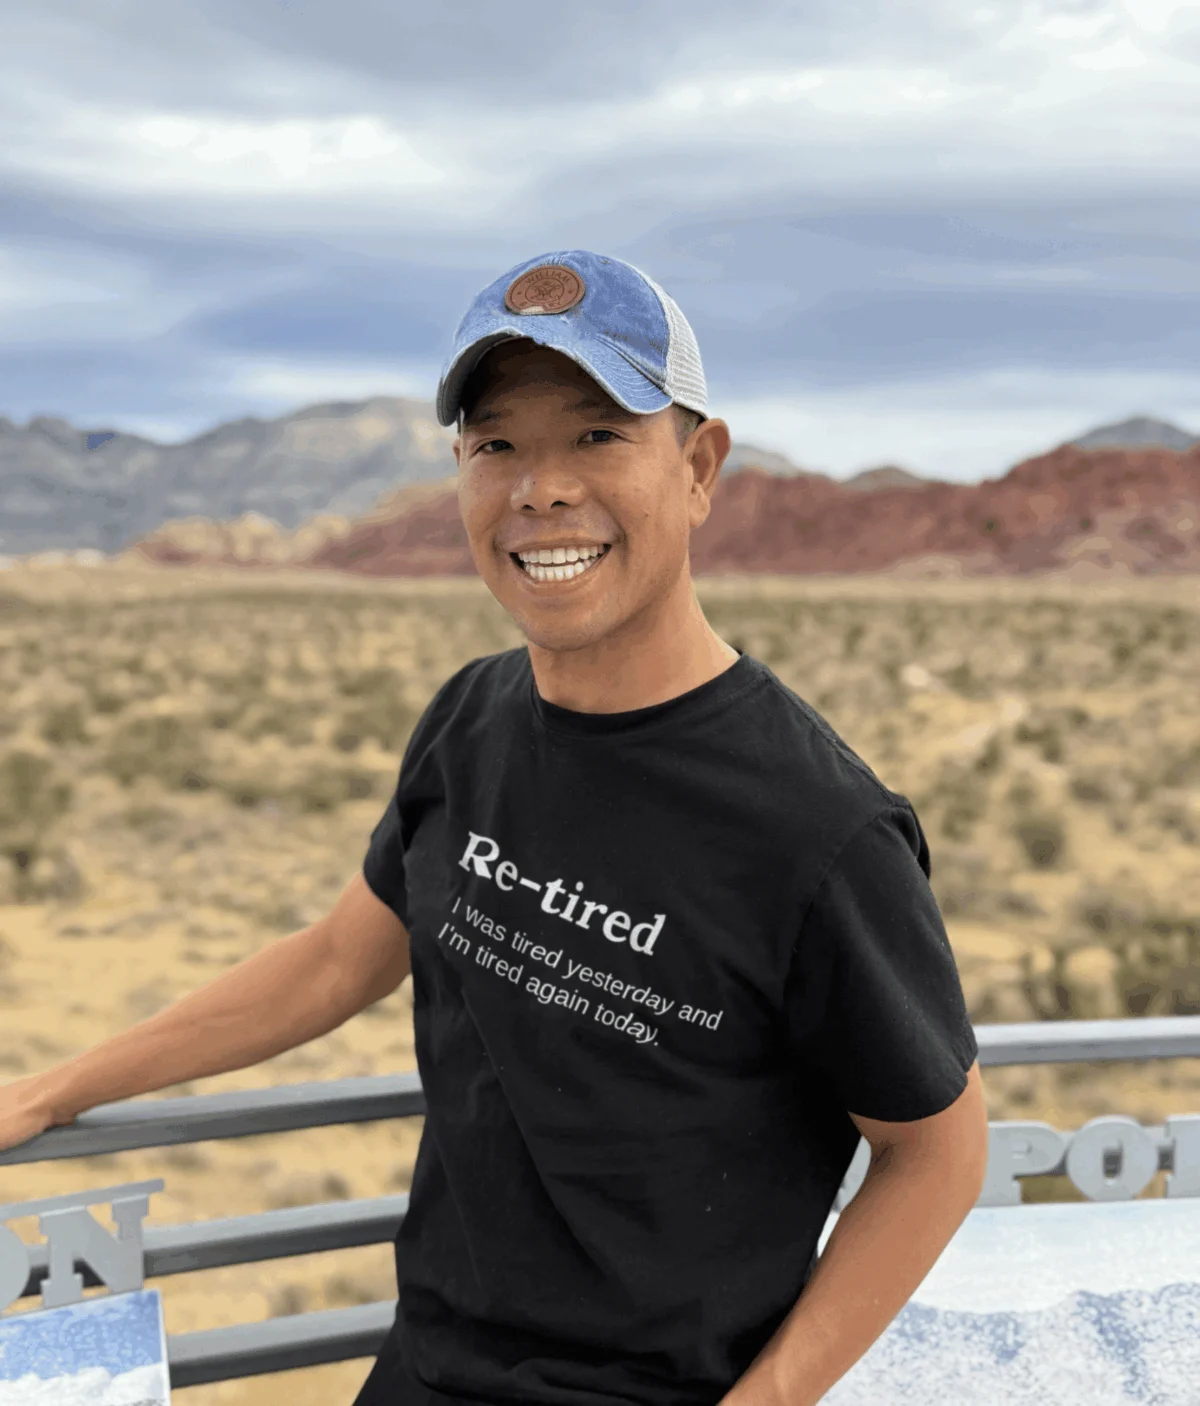
Despite the success of the trip, a minor incident at Red Rocks underscored the lingering effects of the financial stress. After a late night playing poker—where the author suffered a $350 loss—and only four hours of sleep, the author’s patience wore thin.
At a scenic vista, he asked his wife to take portrait photographs. As he began providing specific, "fussy" directions—requesting changes in height, angle, and orientation—the tension became palpable. His wife’s irritation was immediate, and the subsequent silence felt like a rejection.
This moment of friction, while seemingly trivial, was a window into the author’s internal state. He realized that the stress of the capital call, the loss at the poker table, and the sleep deprivation had caused him to project his anxieties onto a simple, shared activity. It was a clear example of how financial strain can magnify minor interactions, transforming a neutral moment into a source of self-doubt and conflict.
Supporting Data and Psychological Implications
The implications of this experience extend beyond one family’s vacation. It speaks to the broader "silent burden" carried by those who view themselves as the sole or primary financial engine of a household.

The Cost of Silence
When providers bury their financial fears to avoid causing worry, they often inadvertently create a vacuum. The partner, unaware of the underlying stress, interprets the provider’s tension as a lack of engagement or a personal critique. This "guessing game" leads to the deterioration of intimacy.
The Evolution of the Provider Role
Modern financial planning is not merely about asset allocation; it is about psychological allocation. The author’s realization—that he was letting one "red position" (a bad trade or an unexpected cost) ruin an otherwise "green portfolio" (the health and happiness of his family)—is a vital lesson for anyone managing significant capital.
The research suggests that when individuals are under high-stress financial obligations, their cognitive bandwidth for emotional regulation decreases. The "fussy fashion photographer" behavior displayed by the author was not a reflection of his true character, but a byproduct of an overtaxed nervous system.
Official Recommendations: A Framework for Financial Providers
To navigate the complexities of providing while maintaining familial harmony, the following strategies have been identified as essential:
1. The Six-Month Cash Buffer
Maintaining a minimum of six months of living expenses in cash or cash equivalents is non-negotiable. This is not just a financial safeguard; it is "emotional capital." It provides the buffer necessary to make decisions from a position of logic rather than fear. In the current economic climate, where short-term Treasuries offer respectable yields, the "opportunity cost" of holding cash is effectively neutralized by the peace of mind it provides.
2. The End of Micro-Optimization
There is a point of diminishing returns in financial frugality. Saving $1,000 is a victory, but spending the duration of a vacation mentally tracking expenses is a loss. The marginal benefit of the saved dollar is quickly outweighed by the cost to one’s mood and relationship quality. Providers must learn to "turn off" the calculator once the budget is set.
3. Transparent Communication
Silence is the enemy of partnership. Providers do not need to share every granular detail of their balance sheet, but they must communicate their emotional state. A simple statement—"I am feeling financially stretched, and it might make me more irritable than usual"—sets expectations and allows the partner to support the provider rather than resent them.
Conclusion: Reframing the Purpose of Wealth
The ultimate takeaway from this experience is a shift in perspective regarding the purpose of investing. Wealth is not merely a collection of assets; it is a tool for creating experiences that define the quality of life. The portfolio of a successful life includes the laughter of children, the beauty of shared vistas, and the strength of a marriage.
For the author, the trip to Las Vegas served as a necessary "forced change." It stripped away the need to optimize every last cent and replaced it with a commitment to presence. By acknowledging the burden of the provider and the necessity of emotional, as well as financial, liquidity, individuals can ensure that their pursuit of future wealth does not come at the expense of their current happiness.
As the author noted in his reflection, "Your kids won’t remember whether you got a great rate on the second room. They’ll remember whether Dad was present or distracted." Moving forward, the goal is clear: to invest in a way that provides for the future without sacrificing the present, ensuring that the "silent burden" of the provider remains exactly that—silent, managed, and secondary to the joy of the family experience.

 Muslim
 Nana

 Ammar Sabilarrohman

 Asep Darmawan

 Asro

 Layla Zulfa

 Nila Kartika Wati

