
 Azzam Bilal Chamdy
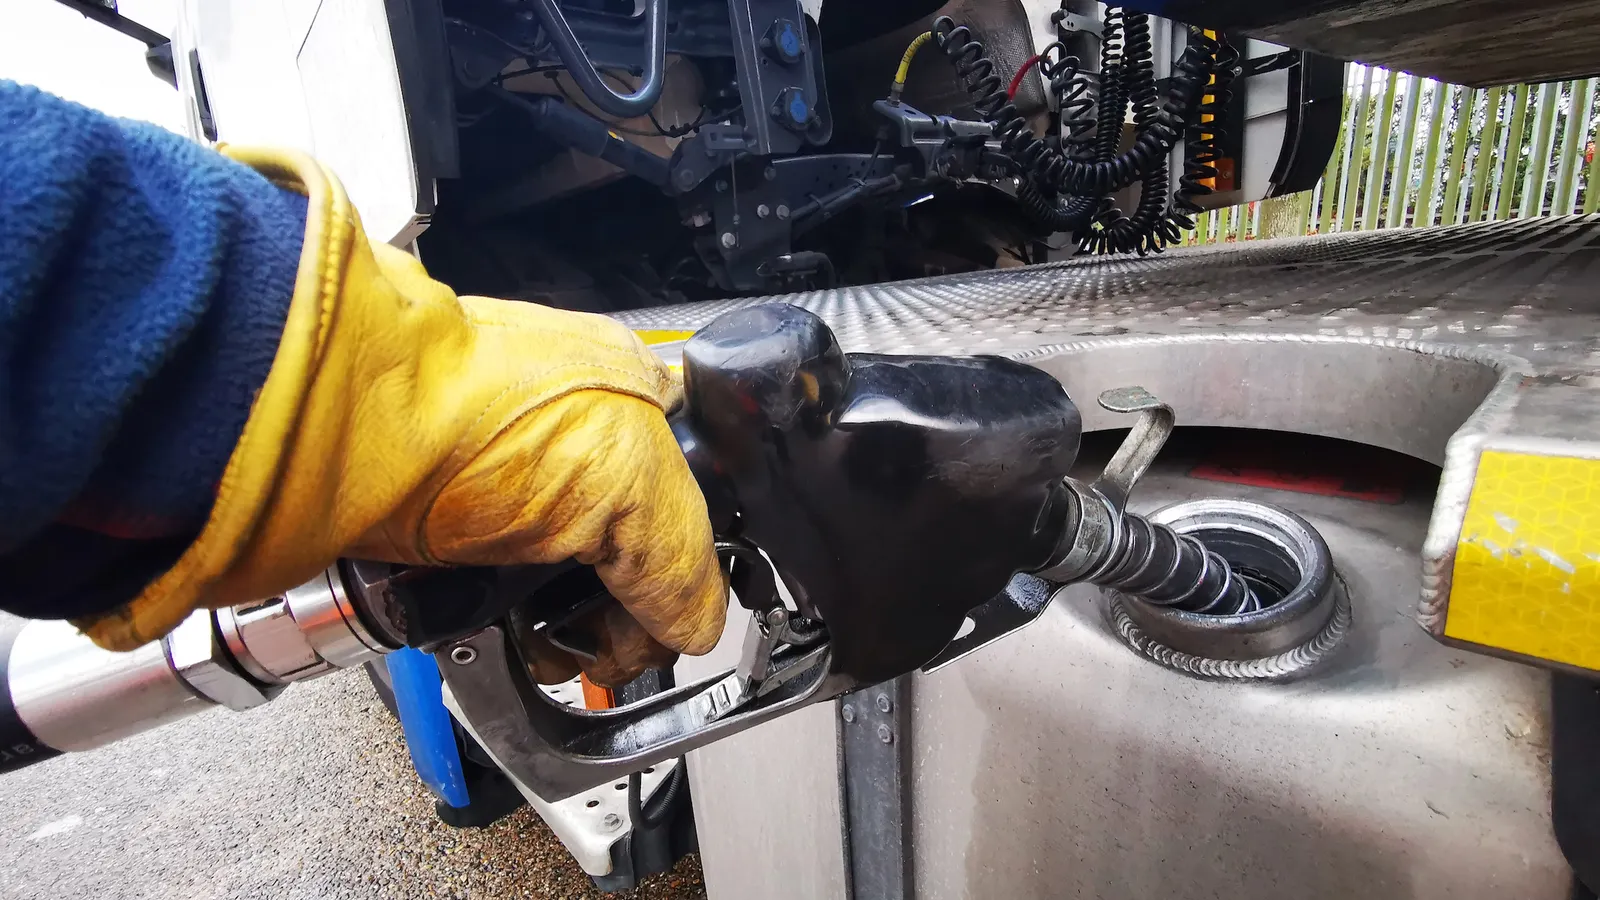
The U.S. logistics landscape is currently navigating a period of intense turbulence, characterized by volatile diesel prices, shifting freight demand, and a growing disconnect between carrier operational costs and existing contract structures. While national average diesel prices have retreated slightly from their recent peaks, the financial relief felt by fleet managers is marginal at best. For CFOs and logistics directors, the current environment serves as a stark reminder of the fragility of global supply chains and the urgency of integrating fuel-risk management into core financial planning.
Main Facts: A Market in Flux
As of October 5, the U.S. average for on-highway diesel stood at $6.20 per gallon, a modest decline from the $6.38 recorded just one week prior, according to the U.S. Energy Information Administration (EIA). Despite this cooling trend, freight rates remain stubbornly elevated, consistently outperforming their historical seasonal averages.
The root of this economic pressure is multifaceted. It is not merely a matter of crude oil pricing; it is a complex interplay of refinery capacity, geopolitical instability, and a mismatch in the velocity of freight recovery versus fleet expansion. As the industry enters a cycle of contract renewals for the coming year, carriers and shippers are locked in a high-stakes tug-of-war, with fuel costs acting as the primary lever of friction.
Chronology: The Escalation of Energy Pressures
The timeline of the current crisis highlights how quickly geopolitical shocks translate to the fuel pump:
- Late Summer 2026: Global tensions, particularly concerning shipping lanes in the Strait of Hormuz and ongoing conflicts impacting Russian refinery output, begin to tighten global diesel supplies.
- Early September 2026: Freight rates show significant strength post-Labor Day, with load-to-truck ratios rising faster than equipment availability.
- September 13, 2026: National spot rates for dry vans, refrigerated trailers, and flatbeds remain significantly higher than their nine-year averages, signaling that carriers are regaining pricing power.
- September 22, 2026: Chevron CFO Eimear Bonner warns at a Wall Street Journal event that price stability is unlikely until shipping predictability in the Middle East improves and global refining capacity expands.
- September 27, 2026: President Trump addresses the impact of Ukrainian strikes on Russian refineries, citing global fuel price spikes. Simultaneously, the White House signals interest in a potential export ban on U.S. diesel.
- September 29, 2026: North Dakota Governor Kelly Armstrong declares a state of emergency, allowing agricultural vehicles to utilize lower-taxed red-dyed diesel on public roads to mitigate rising costs.
- October 1, 2026: Social media-driven calls for a nationwide trucker strike circulate; however, major industry associations dismiss the effort as unorganized digital noise rather than a coherent labor action.
Supporting Data: The Anatomy of a Tight Market
The financial strain on the transportation sector is supported by granular data that illustrates a market operating at peak capacity. According to data provided by DAT and analyzed by Trucking Dive, spot rates in mid-September were substantially higher than historical norms: 20% for dry vans, 28% for refrigerated units, and 25% for flatbeds.
The discrepancy between freight demand and truck supply is the engine behind these elevated rates. During the week of September 13, load postings on the DAT One platform surged by 16% to 2.9 million, while truck postings lagged behind with only an 8% increase. This imbalance is driving carriers to invest in new equipment to capitalize on the demand; trailer orders in August hit 24,144 units, a 43% month-over-month increase, suggesting that fleet operators remain optimistic about long-term freight volume despite the current fuel cost headwinds.
Refining margins, often tracked via the "3-2-1 crack spread"—a metric representing the cost of turning three barrels of crude into two barrels of gasoline and one barrel of diesel—further complicate the picture. Because the price of diesel is decoupled from crude alone, these spreads demonstrate that even if crude oil prices stabilize, diesel may remain expensive due to constraints in the refining sector.
Official Responses and Policy Interventions
State and federal governments have begun to intervene as the economic impact of high fuel costs trickles down to food and medicine prices.
In the states of North Dakota and Texas, governors have issued executive orders waiving restrictions on the use of red-dyed diesel for agricultural and essential logistics transport on public roads. This measure allows for a savings of approximately 19 cents per gallon in state taxes for eligible users, providing a temporary lifeline for local supply chains.
At the federal level, the administration’s response has been more aggressive. President Trump has publicly weighed a potential ban on U.S. diesel exports to keep more supply within domestic borders. However, experts like Andy Lipow of Lipow Oil Associates caution that such a move could backfire. A ban might lower domestic prices temporarily, but it could force Gulf Coast refiners to throttle crude processing once storage capacities are filled, ultimately reducing the output of other critical fuels, including gasoline. Furthermore, the U.S. government’s release of up to 40 million barrels of crude from the Strategic Petroleum Reserve (SPR) is a move aimed at market stabilization, though the efficacy of this strategy is limited by the physical constraints of the refining process.
Implications for Finance and Logistics
For the modern corporation, the "diesel problem" has shifted from a line-item concern to a strategic imperative. The current volatility exposes the limitations of legacy fuel surcharge agreements. As noted by American Trucking Associations Chief Economist Bob Costello, many surcharges are tied to lagging EIA price indices, leaving carriers exposed to mid-week price spikes that they cannot immediately pass on to shippers.
The CFO’s New Reality
Finance teams are increasingly moving away from passive fuel management. At companies like Wayfair, the intersection of logistics and finance has become a focal point, with CFOs advocating for the use of artificial intelligence to audit freight bills and optimize routing. The goal is to move beyond the "pandemic hangover" mindset and build a more resilient infrastructure that can withstand global energy shocks.
The Human and Economic Cost
Beyond the balance sheet, there is an underlying concern about the stability of the workforce. While the threatened "October 1 strike" failed to materialize into a systemic industry halt, the underlying sentiment—that operators are feeling the pinch of rising costs—is real. Carriers like Swint Logistics Group have reported that even when clients attempt to assist with extra work hours, it is a band-aid solution, not a cure for the structural imbalances caused by high fuel prices.
As winter approaches, the challenge will only intensify. Diesel is fundamentally linked to home heating oil; as the Northeast prepares for colder temperatures, domestic inventories of distillates are expected to tighten further. This "dual demand"—for both transportation and residential heating—creates a potential for further price volatility.
Conclusion: Preparing for a Volatile Future
The current diesel crisis is a macro-level event with micro-level consequences. From the individual trucker struggling to maintain profit margins to the global retailer re-evaluating their fulfillment strategy, the message is clear: the era of predictable fuel costs has ended.
Success in the coming fiscal year will belong to those who can master the volatility. This requires more than just reactive surcharges; it demands a proactive approach to supply chain visibility, a sophisticated understanding of energy market mechanics, and a willingness to collaborate across the entire logistics ecosystem. Until the global geopolitical landscape stabilizes and refinery output catches up with global demand, finance and logistics teams must treat fuel volatility not as an anomaly, but as a permanent variable in their business models.

 Basiran
 Neng Nana
 Lina Hope
 Nila Kartika Wati
 Sagoh
 Pevita Pearce
 Reynand Wu
 Ali Ikhwan
