
 Azzam Bilal Chamdy
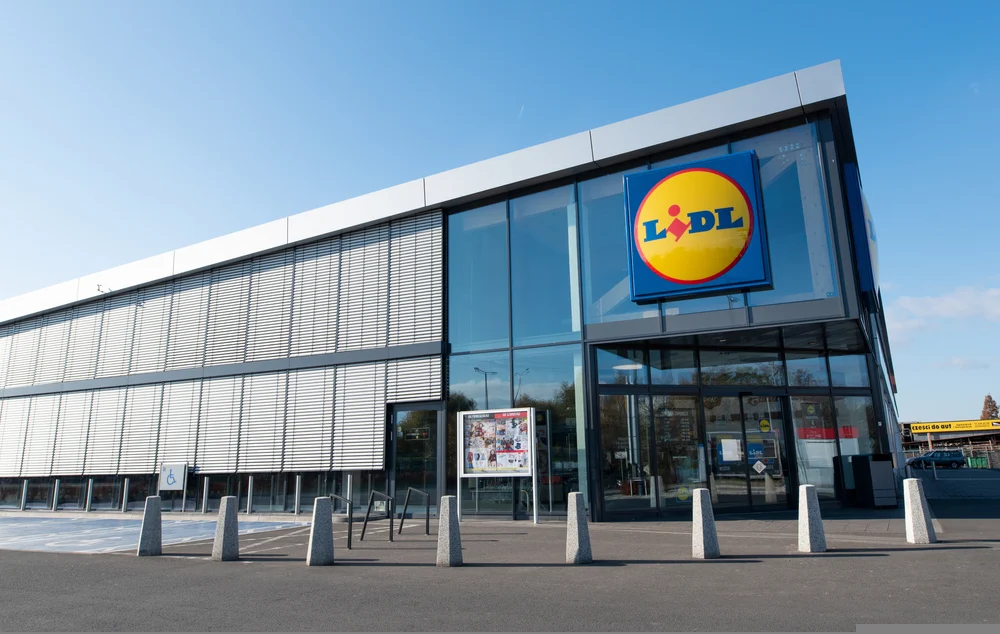
In the shifting sands of the British retail sector, a quiet revolution has been underway. As the United Kingdom navigates the persistent headwinds of the cost-of-living crisis, household budgets have been squeezed, forcing a fundamental rethink of consumer shopping habits. At the heart of this transformation is Lidl GB, which has emerged as the primary beneficiary of a widespread "flight to value."
According to the latest financial disclosures, the German-owned discounter has generated more than £650 million in sales purely from shoppers switching away from traditional "Big Four" supermarkets. This massive shift in market share underscores a broader trend: the middle-class consumer, once loyal to premium or established household brands, is now prioritizing price and efficiency above all else.
The Financial Powerhouse: Record-Breaking Growth
The fiscal year ending 28 February 2026 has been a landmark period for Lidl GB. The company’s turnover surged by 10.8 per cent, reaching a staggering £13 billion, up from £11.7 billion in the previous financial year. This growth is not merely a product of inflation—where higher prices drive higher revenue—but a result of genuine volume expansion.
The retailer reported 43 million additional customer visits during the period, a figure that highlights a deepening penetration into the British market. Furthermore, the volume of goods shifted—measured by the number of individual products sold—rose by 486 million units. This surge in footfall and transaction volume has been bolstered by strong performances in core categories such as fresh meat, poultry, and produce, as well as a surprising 12 per cent uptick in sales of its premium "Deluxe" range. The latter statistic suggests that while shoppers are budget-conscious, they are not willing to sacrifice quality; they are simply seeking more affordable avenues to enjoy premium experiences at home.
Chronology of a Discounter’s Rise
Lidl’s ascent has been methodical, fueled by a long-term strategy of aggressive pricing and infrastructure investment.
- Mid-2025: As inflation remained a persistent thorn in the side of the average British household, Lidl ramped up its marketing campaigns, focusing on "swaps"—encouraging shoppers to replace branded goods with own-label equivalents.
- May 2026: In a historic milestone, industry data confirmed that Lidl had officially overtaken Morrisons to become the UK’s fifth-largest grocer by market share. Reaching 8.7 per cent of the market, the discounter proved it had moved beyond its status as a "niche" alternative.
- Late 2026: Lidl intensified its commitment to the consumer by announcing a further £400 million investment in price cuts and seasonal promotions, timed specifically to capture the lucrative Christmas spending period.
- Current Standing: With pre-tax profits jumping 31.1 per cent to £205.5 million and operating profits climbing to £345 million, Lidl is entering the next fiscal year with a robust balance sheet that provides the liquidity to further undercut competitors.
Comparative Performance: The "Big Four" Under Pressure
The contrast between Lidl’s trajectory and the performance of the UK’s legacy supermarkets is stark. For years, the traditional grocery giants have struggled to reconcile the need for profit margins with the demand for competitive pricing.
In their most recent financial reports, the disparity became clear:
- Tesco: While still the market leader, Tesco saw sales grow by a modest 4.6 per cent.
- Sainsbury’s: Reported a growth rate of 4.3 per cent.
- Morrisons: Trailed significantly with revenue growth of just 3.2 per cent.
- Asda: Faced a contraction, with sales falling by 3.3 per cent.
These figures illustrate a painful reality for legacy retailers. While they maintain massive scale and supply chain advantages, they are increasingly vulnerable to the nimbleness of discounters. Lidl’s model, which relies on a smaller product range and high-efficiency logistics, allows them to maintain lower price points without eroding profitability to the same extent as their larger, more complex rivals.
The Strategy: Investing in the Consumer
Lidl’s success is not accidental; it is the result of a deliberate, well-funded strategy. Chief Executive Ryan McDonnell has been vocal about the retailer’s philosophy. By maintaining a predominantly own-label range, Lidl keeps its supply chain streamlined and its overheads low. This allows the business to reinvest significant capital back into the price of goods.
During the last financial year alone, Lidl invested £315 million in price cuts and promotions. This commitment was recently expanded with a £400 million pledge aimed at maintaining this momentum. This "price-first" strategy serves a dual purpose: it incentivizes new customers to try the store for the first time, and it fosters loyalty among existing shoppers who feel the retailer is "on their side" during difficult economic times.
Implications for the Grocery Sector
The rise of Lidl holds profound implications for the future of British retail.
1. The Death of Brand Loyalty?
The data suggests that brand loyalty is becoming a luxury. As shoppers continue to switch, the "own-label" movement is gaining ground. Retailers that rely heavily on third-party branded goods are finding it harder to compete with the margin-defending strategies of discounters.
2. The Premiumization of Discounters
The 12 per cent growth in the "Deluxe" range is a bellwether for the retail industry. It suggests that the stigma once associated with discount shopping has evaporated. Middle-income families are increasingly comfortable hosting dinner parties or celebrating special occasions using goods sourced from Lidl, effectively democratizing premium food and drink.
3. Supply Chain Agility
Lidl’s growth forces a conversation about efficiency. The traditional "Big Four" have thousands of SKUs (Stock Keeping Units) and vast, complex supply chains. Lidl’s more focused range allows for better inventory turnover and reduced waste. As inflation and supply chain disruptions persist, the discounter’s model is increasingly being viewed as the "gold standard" for resilience in a volatile market.
4. Continued Consolidation
If the current trend persists, further shifts in market share are inevitable. With Lidl now firmly entrenched as the fifth-largest player, the pressure on the bottom tier of the traditional supermarkets will only intensify. This may lead to further consolidation or radical structural changes within the sector as legacy firms look to find ways to compete with the discounter’s cost base.
Conclusion: A New Equilibrium
The figures speak for themselves: £650 million in switched sales is a monumental shift that signals a permanent change in the UK grocery landscape. Lidl is no longer just a "budget" option; it has become a central pillar of the British retail economy.
As the supermarket chain looks to the future, the challenge will be to maintain this growth without sacrificing the very efficiencies that made it successful. For now, however, Ryan McDonnell and his team have demonstrated that in an era of uncertainty, the most effective business strategy is to simplify the shopping experience and provide unwavering, tangible value to the consumer. Whether the traditional giants can pivot fast enough to stem the tide remains the most significant question in British retail for the year ahead.


 Rifan Muazin
 Asro

 Raul Delapena Setiawan

 Dwi Wanna

 Muslim

 Nana Wu

