
 Dwi Wanna
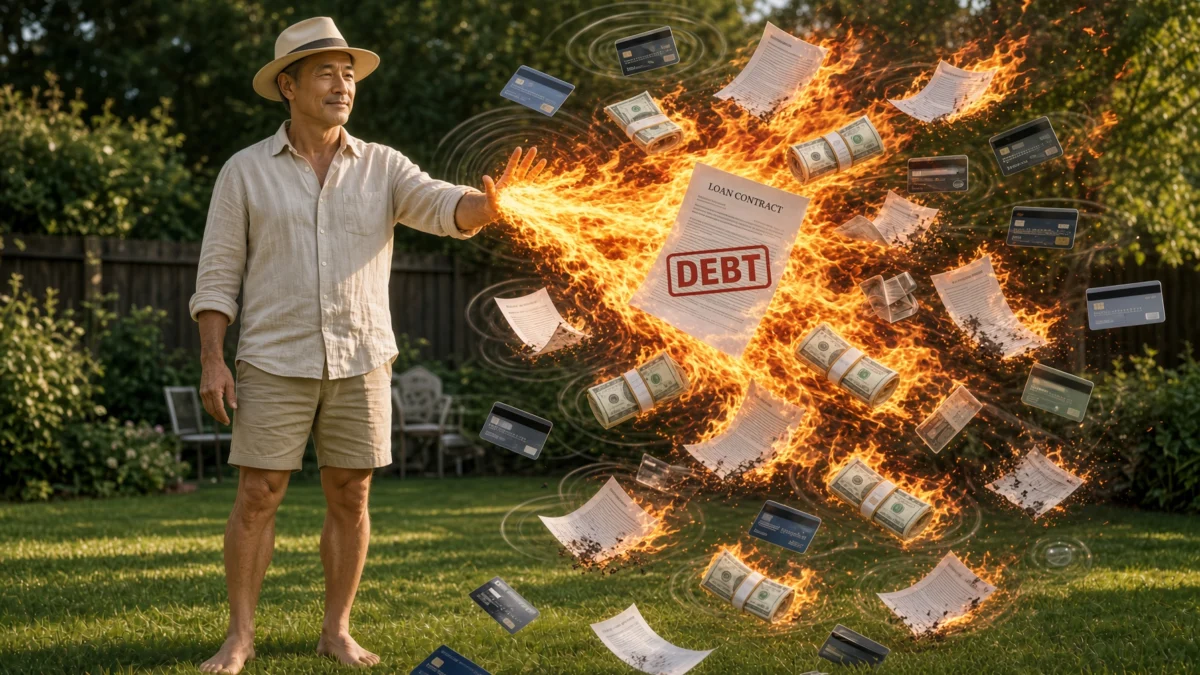
For those who have achieved Financial Independence, Retire Early (FIRE), the concept of debt often shifts from a tactical financial tool to a psychological burden. Recently, this tension was laid bare when a high-net-worth investor—who reached FIRE status in 2012—found himself facing an unexpected liquidity crunch caused by the aggressive capital deployment of a venture capital fund.
The situation serves as a masterclass in the risks of private equity, the psychological weight of early retirement, and why the "smart" financial move on paper is often the one that feels most wrong to the FIRE community.
Main Facts: The Capital Call Miscalculation
The crisis began with a simple, albeit costly, projection error. After committing $1 million to a venture capital fund, the investor anticipated a conservative call schedule—roughly 30% of the total commitment during the first year. Instead, the fund accelerated its deployment, calling 46% of the commitment in just six months.
On a $1 million commitment, this created a $160,000 "timing gap." While the funds were technically available, they were tied up in other assets, forcing the investor to confront a sudden, unplanned liquidity requirement.
The dilemma highlighted a fundamental conflict: Should an investor leverage their portfolio to satisfy a call, or should they liquidate assets, triggering capital gains taxes, to fund an illiquid investment?
A Chronology of the Liquidity Crunch
The Initial Commitment (The Setup)
The investor entered the venture capital agreement under the assumption that capital calls would be spread out over several years. This is standard practice in the industry, allowing limited partners to manage their cash flow effectively. At the time of signing, the commitment represented a deliberate allocation of roughly 20% of the investor’s total liquid assets, a move intended to diversify into high-growth, albeit illiquid, private markets.
The Six-Month Acceleration (The Trigger)
Within half a year, the venture manager deployed capital significantly faster than anticipated. When the call for $460,000 arrived—surpassing the anticipated $300,000 mark by a significant margin—the investor was forced to reconsider his cash management strategy.
The "Debt" Proposal (The Reader Response)
As the investor publicized his scramble to tighten expenses, a reader offered a sophisticated, institutional-grade solution: a Pledged Asset Line (PAL) or a Liquidity Access Line (LAL). These instruments allow investors to borrow against their brokerage portfolio, using stocks and bonds as collateral, without triggering capital gains taxes by selling the underlying assets.
The Retrospective Analysis (The Realization)
Upon reviewing the suggestion, the investor realized he hadn’t even considered borrowing. His post-FIRE mindset had effectively "deleted" debt as a viable option, a discovery that forced him to evaluate whether his aversion to debt was a badge of honor or a missed financial opportunity.
Supporting Data: The Cost of Capital vs. The Cost of Freedom
To understand why this is a dilemma, one must look at the mechanics of borrowing against assets.
- The PAL Mechanics: Pledged Asset Lines typically charge variable rates, currently ranging between 7% and 10%.
- The Opportunity Cost: Borrowing $160,000 at an 8% interest rate equates to an annual interest expense of approximately $12,800.
- The Risk Multiplier: Unlike traditional fixed-rate loans, PALs are subject to margin calls. If the underlying portfolio value drops—as often happens during economic downturns—the lender can demand immediate repayment or additional collateral. Because capital calls often intensify when markets are distressed (as venture managers look to scoop up cheap deals), relying on debt can create a "doom loop" where a market crash triggers both a margin call and a capital call simultaneously.
Historically, those who reach FIRE have been obsessed with "net worth acceleration." However, once the "Enough Number" is reached, the focus shifts. Data from the FIRE community suggests that once active income is replaced by passive income, the appetite for risk—and the tolerance for debt—collapses.
Official Perspective: The "Buy, Borrow, Die" Strategy
The suggestion to use a PAL mirrors a strategy often used by the ultra-wealthy. Often referred to as "Buy, Borrow, Die," this tax-optimization strategy involves:
- Buying assets that appreciate.
- Borrowing against those assets to fund lifestyle or business needs (avoiding capital gains taxes).
- Dying, at which point the assets receive a "step-up in basis," effectively erasing the capital gains tax liability for heirs.
While this is mathematically superior for tax efficiency, the investor argues it is antithetical to the FIRE philosophy. For the retired individual, the goal is not to maximize wealth at the expense of simplicity; it is to maximize freedom.
Implications: Why Debt Feels Like Walking Backward
The psychological implications of this scenario are profound. When an individual achieves financial independence, they effectively "exit the game." Re-entering the debt market feels like an admission of failure.
1. The Decumulation Struggle
In the accumulation phase of life, debt is an engine. In the decumulation phase—the process of spending down wealth—debt is an anchor. The investor notes that when your net worth is significantly higher than it was at the moment of retirement, taking on debt to invest feels empty. It creates a disconnect: you are working to maintain a portfolio that is supposed to serve you, not one that you are forced to serve.
2. The Opportunity Cost of Time
The most compelling argument against taking on debt to fund long-term, illiquid venture investments is the "Golden Window." For parents, the time available to spend with children is limited to roughly 12 to 15 years of childhood. Engaging in complex, interest-bearing debt maneuvers to fund a venture capital fund that may not pay out for over a decade risks prioritizing hypothetical future wealth over tangible, present-day freedom.
3. The "No-Debt" Dogma
The investor concludes that while he is not dogmatic about existing debt—citing the utility of low-interest mortgage debt—he is strictly opposed to new debt. His rationale is clear: debt is an obligation. Obligations are the antithesis of the freedom that the FIRE movement promises.
Conclusion: A Lesson for the FIRE Community
The venture capital capital-call crisis serves as a poignant reminder that financial independence is not merely a number; it is a lifestyle.
For the reader, the "smart" move was to borrow at 8% to preserve his portfolio. For the investor, the "right" move was to recognize that if his current liquidity necessitated debt, he had already reached the limit of his investment comfort zone.
As the FIRE movement continues to grow, more individuals will find themselves managing complex private investments alongside their retirement portfolios. The lesson here is that as you transition from wealth builder to wealth manager, the most valuable asset you own is your lack of obligations. Before taking on debt, ask yourself: are you borrowing to reach your goals, or are you borrowing because you’ve forgotten that you’ve already reached them?
Ultimately, the goal of early retirement is to stop walking backward. If a financial instrument requires you to leverage your future to chase an uncertain return, it is likely a step in the wrong direction, no matter what the math says.

 Ali Ikhwan
 Layla Zulfa

 Laily UPN

 Iffa Jayyana

 Rifan Muazin

 Suro Senen

 Lina Hope

 Lina Irawan
