
 Raul Delapena Setiawan
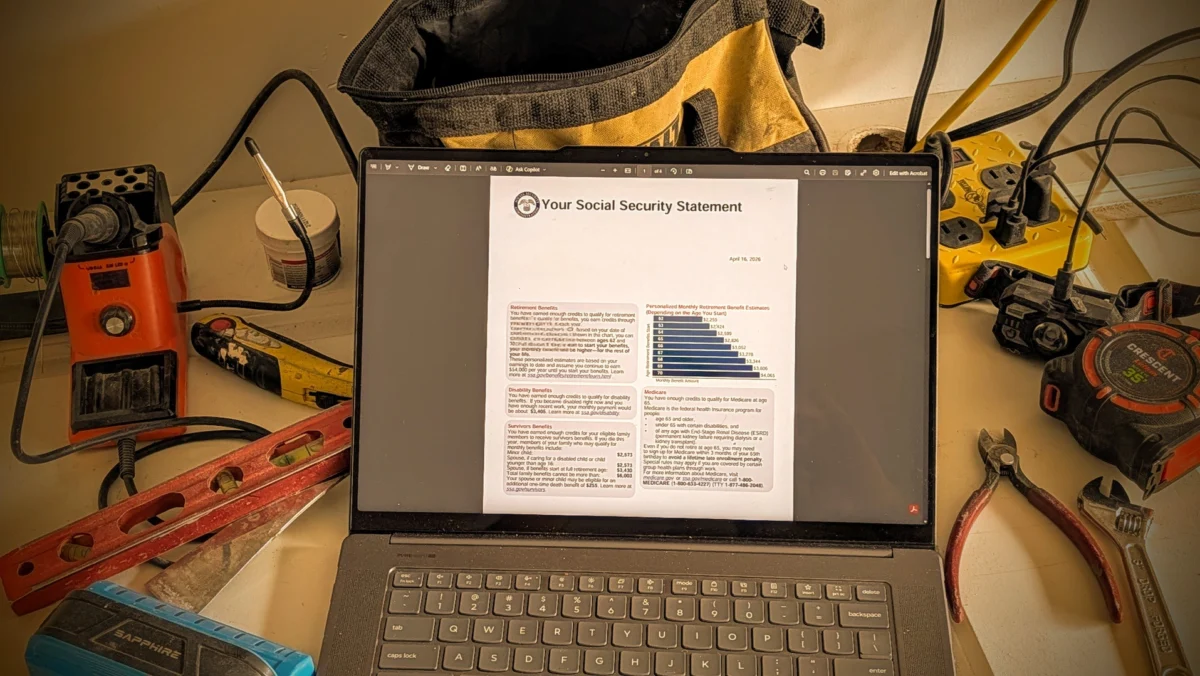
In the pursuit of Financial Independence, Retire Early (FIRE), the narrative is often dominated by index funds, real estate, and the "4% rule." For those planning to exit the workforce in their 30s or 40s, Social Security is frequently dismissed as a peripheral concern—a "fuzzy concept" relegated to a distant, uncertain future. Yet, as the FIRE movement matures, a critical realization is emerging: Social Security is not merely a government safety net; it is a powerful, inflation-adjusted financial instrument that can significantly alter one’s retirement math.
By applying the principles of Net Present Value (NPV), retirees can bridge the gap between their "stash" and their long-term security, potentially unlocking years of additional freedom.
The Core Concept: Redefining Social Security as Capital
For the average worker, Social Security is a paycheck replacement. For the early retiree, however, it is better understood as a deferred asset. If you are thirty-five, retirement isn’t about waiting for a government check; it is about building a portfolio that sustains you until that check arrives—and acknowledging that the check itself is a form of "phantom wealth" that reduces the burden on your personal savings.

The crucial mathematical tool here is the Net Present Value (NPV). In finance, NPV allows us to determine the current value of a future stream of payments. By calculating what your future Social Security benefits are worth in today’s dollars, you can adjust your "safe withdrawal rate" and gain a more accurate picture of your true net worth.
Chronology of a Strategy: From Early Retirement to Eligibility
To understand the utility of this approach, one must look at the timeline of a typical career and retirement trajectory:
- The Early Years (30s–40s): The retiree focuses entirely on aggressive accumulation. At this stage, the NPV of Social Security is effectively zero. Because the payout is three decades away, the risk of government policy changes is high, and the need for immediate liquidity is paramount.
- The Transition (50s): The "math" begins to shift. As the retiree approaches the age of eligibility (62), the discount rate—the time one must wait to receive the money—shrinks. The benefit becomes a tangible hedge against inflation.
- The Golden Years (62+): Social Security becomes a primary income pillar. For those with a low cost of living, these payments can theoretically cover 100% of essential expenses, effectively insulating the retiree from market volatility.
Supporting Data: The Power of the NPV Formula
The math behind this is straightforward. If you are 30 years old and aiming for a monthly payout, you must discount that future income based on inflation and interest rates.

Consider a 30-year-old couple aiming for a $4,000 monthly benefit starting 32 years from now. By calculating the NPV of a 30-year stream of payments and discounting it for the 32-year wait, you arrive at an approximate value of $98,280.
What does this mean for your spreadsheet?
It means that you don’t need to save that $98,280 in your private investment account. It is effectively "pre-saved" for you by your contributions to the system. This provides a safety margin that most early retirees ignore, often leading them to work longer than necessary.
The "Shane Survivor" Case Study
Consider a 55-year-old individual, "Shane," who has seen his savings fluctuate due to business challenges. Standard financial advice dictates that Shane should work until age 67 or 70 to maximize his Social Security payout. However, a deeper analysis reveals a counterintuitive truth: the "cost" of waiting to retire to get a higher payout often outweighs the benefit.

If Shane retires at 62 and invests his payouts, the power of compound interest—coupled with the ability to live off a smaller, existing "stash"—can put him in a stronger position than if he had slogged through five more years of unwanted employment. By capturing the earlier payments, the retiree benefits from a "snowball effect" that the long-term worker, who delays income in favor of a slightly higher future payout, cannot easily replicate.
The Reality of Contributions: Debunking the "Zero" Myth
A common misconception among early retirees is that a short career (e.g., 10 years) will result in a near-zero Social Security payout because the system calculates benefits based on a 35-year average of earnings.
While the system does look at 35 years, it treats years of non-employment as zeros. However, due to the progressive nature of the Social Security benefit formula, the "replacement rate" for lower lifetime earnings is significantly higher than for high earners. Even with a career of only 10 to 15 years, an individual will still receive a meaningful benefit. The "mild incentive for slacking," as some have dubbed it, means that after a certain point, the marginal gain of working an extra year is relatively small compared to the benefit of immediate retirement.

Implications for Financial Planning
The integration of Social Security into a FIRE strategy has three major implications:
- Lowering the Required Stash: If you calculate the NPV of your expected Social Security, you can subtract that figure from your target "FIRE number." This lowers the bar for retirement, potentially moving your retirement date forward by years.
- Psychological Security: Acknowledging the existence of this future floor provides a sense of stability. Even if the market performs poorly, the "guaranteed" nature of Social Security (which is backed by the government and indexed to inflation) provides a psychological safety net.
- Reframing the "Fairness" Debate: Many express concern that Social Security may be reduced or means-tested in the future. While this is possible, the impact is likely to be concentrated on high-net-worth individuals. If your retirement planning is so robust that you are classified as "wealthy," you have already succeeded. Viewing potential cuts as a "tax on the successful" is a more productive mindset than allowing fear to dictate your work-life balance.
Official Perspectives and Public Discourse
The Social Security Administration (SSA) encourages all citizens to create an account at ssa.gov. This is the only way to obtain accurate projections based on your specific earnings history. Official reports from the Social Security Board of Trustees highlight the system’s longevity, though they acknowledge that future adjustments—such as tax increases or benefit modifications—may be necessary to maintain solvency.
Despite these headlines, financial planners generally advise that while the magnitude of benefits might change, the existence of the program as a foundational pillar of American retirement is unlikely to disappear. It remains the most reliable annuity-style product available to the average citizen.

Conclusion: Take Action Today
The most actionable step for any reader, regardless of their proximity to retirement, is to quantify their benefits.
- Log into SSA.gov: Familiarize yourself with your earnings record and your projected monthly benefits at age 62, 67, and 70.
- Run the NPV: Use an online calculator to determine the present value of those payments.
- Adjust Your Spreadsheet: Add this "phantom asset" to your retirement planning. You may be surprised to find that you are closer to your goal than you previously thought.
In the end, retirement is not about the accumulation of an arbitrary dollar amount. It is about reaching a point where your time is your own. By understanding the role of Social Security, you can stop treating it as a distant government promise and start utilizing it as the strategic asset it truly is. Your future self—the one who gets to spend more time with family, traveling, or pursuing passions—will thank you for doing the math today.

 Ali Ikhwan
 Layla Zulfa

 Laily UPN

 Iffa Jayyana

 Rifan Muazin

 Suro Senen

 Lina Hope

 Lina Irawan
