
 Siti Muinah
For many high-net-worth individuals and diligent savers, managing personal finances has long been a tedious, manual labor of love. It typically involves a complex mosaic of spreadsheets, multiple brokerage logins, disparate bank accounts, and the occasional, anxiety-inducing late-night calculation regarding tax liabilities or retirement readiness. Managing over 40 financial accounts across a single household is not just a logistical burden; it is a cognitive one.
However, a new frontier in fintech is emerging: the AI-native financial advisor. Leading this charge is Mezzi, an AI-powered platform that acts as a personalized, 24/7 intelligent sounding board for complex financial decision-making. By synthesizing fragmented data into actionable, fiduciary-grade advice, Mezzi is fundamentally changing how investors approach wealth.

Main Facts: The Intersection of AI and Fiduciary Duty
At its core, Mezzi is an SEC-registered investment advisor that leverages artificial intelligence to provide personalized financial guidance. Unlike traditional "robo-advisors" that merely automate portfolio rebalancing within their own ecosystem, Mezzi is designed to sit on top of your existing financial life.
The platform connects to your existing accounts, treats your assets as a unified whole, and provides specific recommendations—not just generic educational content. Whether it is identifying tax-loss harvesting opportunities, flagging hidden stock concentration risks, or calculating the viability of an early retirement date, Mezzi operates with the rigor of a human professional but the speed and availability of a digital assistant.
The platform is built on three pillars:
- Aggregation and Context: By linking all accounts, Mezzi builds a "financial brain" that understands the nuance of your income, spending, and goals.
- Active Monitoring (Delegations): Users can assign ongoing "jobs" to the AI, such as monitoring taxable accounts for losses or tracking specific stock exposure.
- Fiduciary Personalization: As an SEC-registered entity, Mezzi’s recommendations are held to a fiduciary standard, ensuring that the advice provided is meant to serve the user’s best interests.
Chronology: A Shift from Spreadsheet to Strategy
The evolution of personal finance management has traveled from physical ledgers to Excel spreadsheets, and finally to the current era of AI integration.

- The Manual Era: For years, the standard for managing wealth involved manual data entry. Investors would spend hours on weekends updating net worth statements, calculating tax impacts, and attempting to manually diversify holdings across various institutions.
- The Aggregation Era: The rise of platforms like Mint (and later its successors) allowed users to view their accounts in one place. However, these tools remained passive; they showed you what you had, but rarely offered advice on what to do about it.
- The AI-Native Era (Present): With the introduction of Mezzi, the industry has moved into the advisory phase. By using Large Language Models (LLMs) tuned for financial data, the platform allows users to engage in a back-and-forth dialogue—asking, for example, "Does it make sense to sell $50,000 of Google to diversify into an index fund?" and receiving a detailed, tax-aware breakdown of the trade-offs.
Supporting Data: Why AI Outperforms the "Guesswork" Model
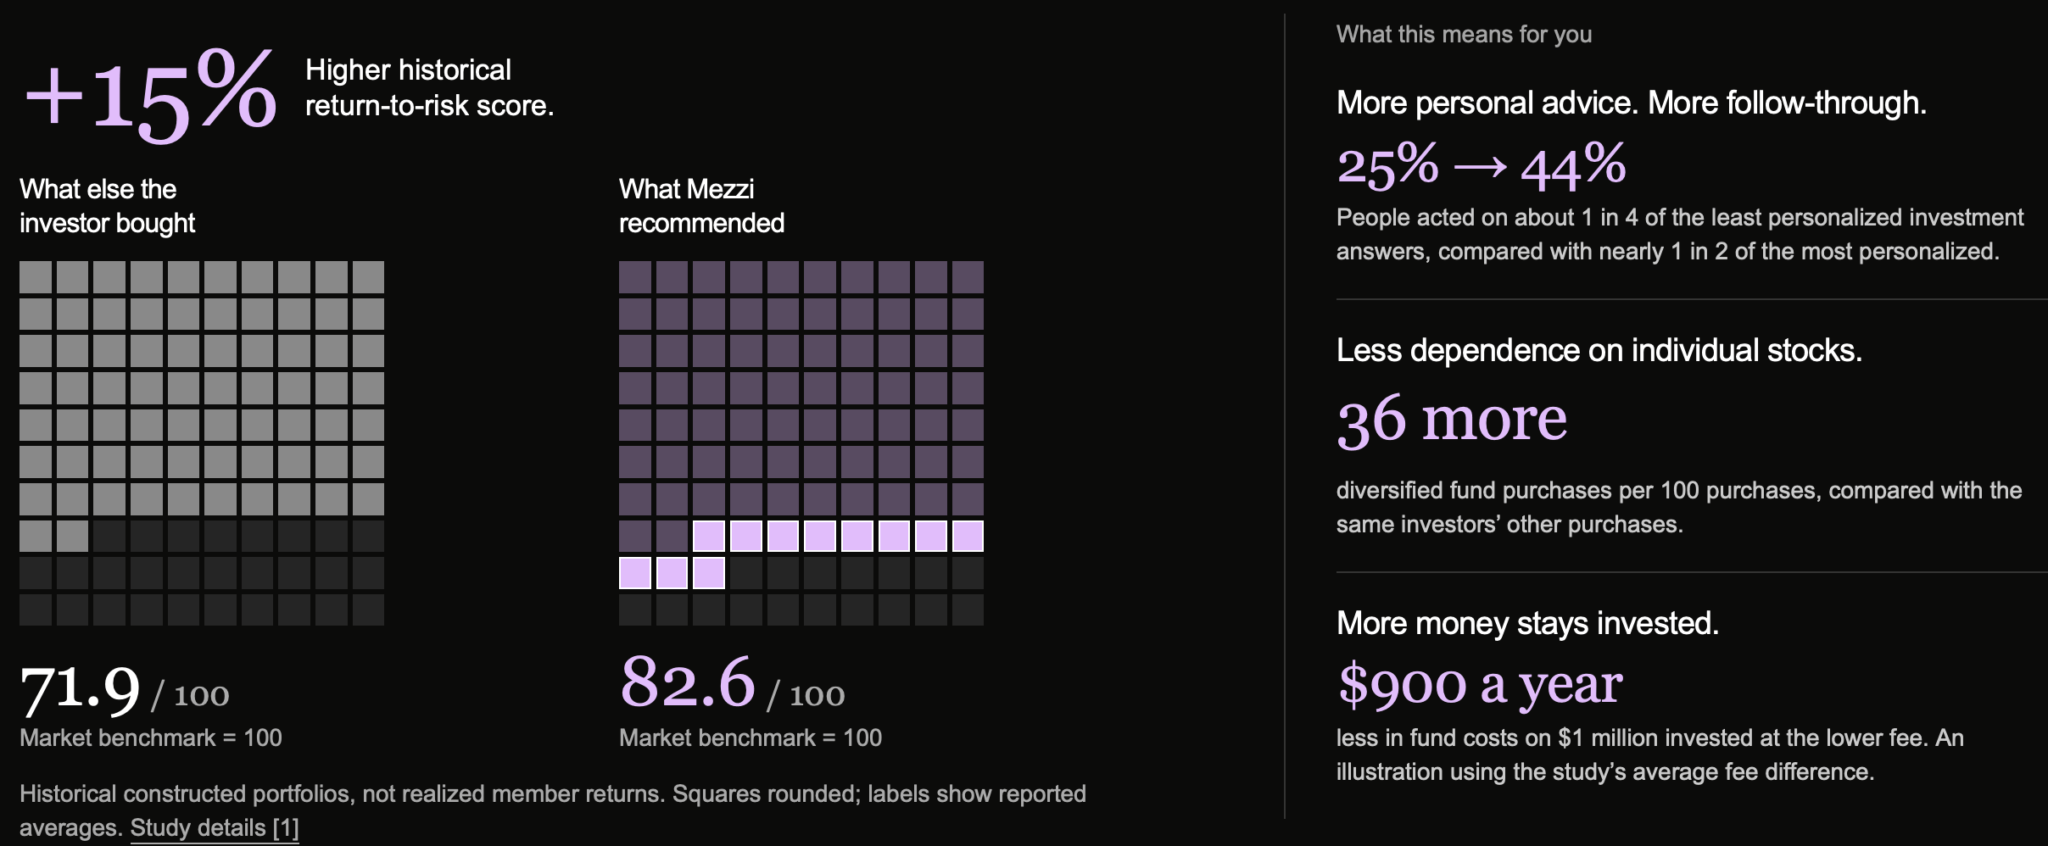
The efficacy of AI in this space is no longer theoretical. A recent study by NYU Stern researcher Valerie Baldinger provided a deep dive into Mezzi’s impact on member investment behavior and portfolio outcomes over a five-year historical period.
The data suggests that when users follow Mezzi’s recommendations:

- Risk-Adjusted Returns: Portfolios built using Mezzi’s guidance demonstrated approximately 15% stronger risk-adjusted results compared to the investors’ own independent purchases.
- Cost Efficiency: Users shifted more capital toward low-cost index funds, resulting in a reduction of annual expense ratios by roughly 0.09 percentage points.
- Diversification: The "Diversification X-ray" feature proves that many investors suffer from "hidden concentration"—owning the same tech giant through five different mutual funds and individual stock holdings simultaneously. Mezzi helps uncover these overlaps, allowing for smarter, more intentional asset allocation.
The Hypothetical Household: A Case Study in Complexity
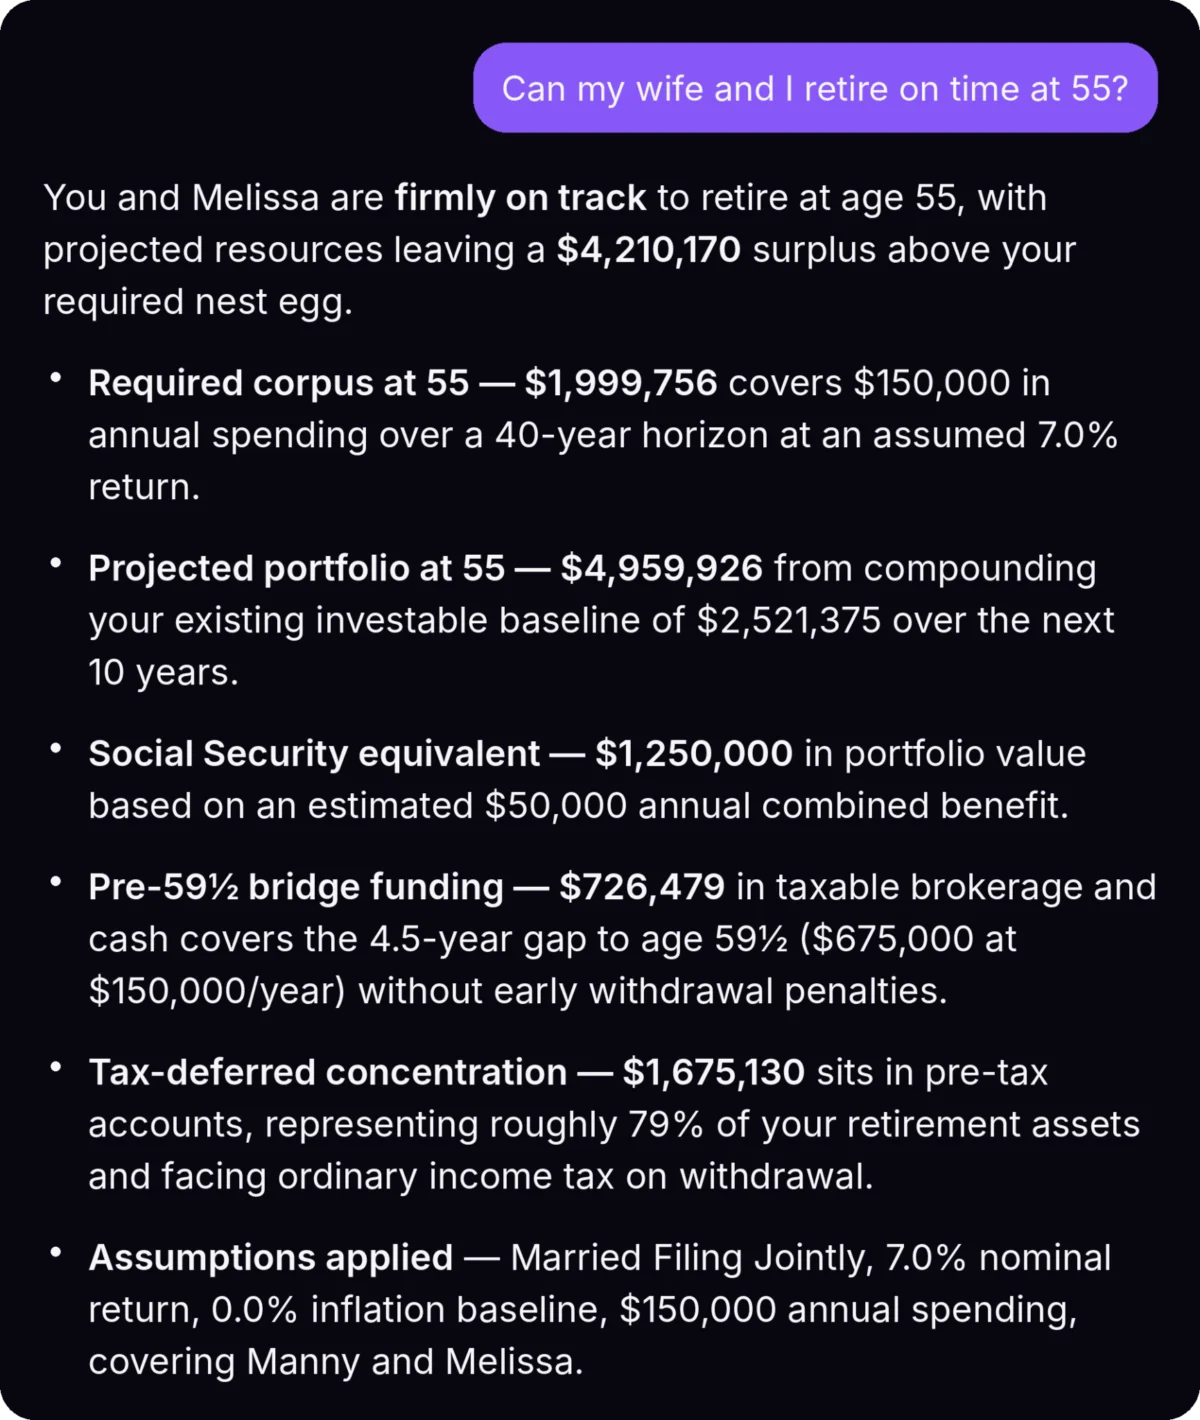
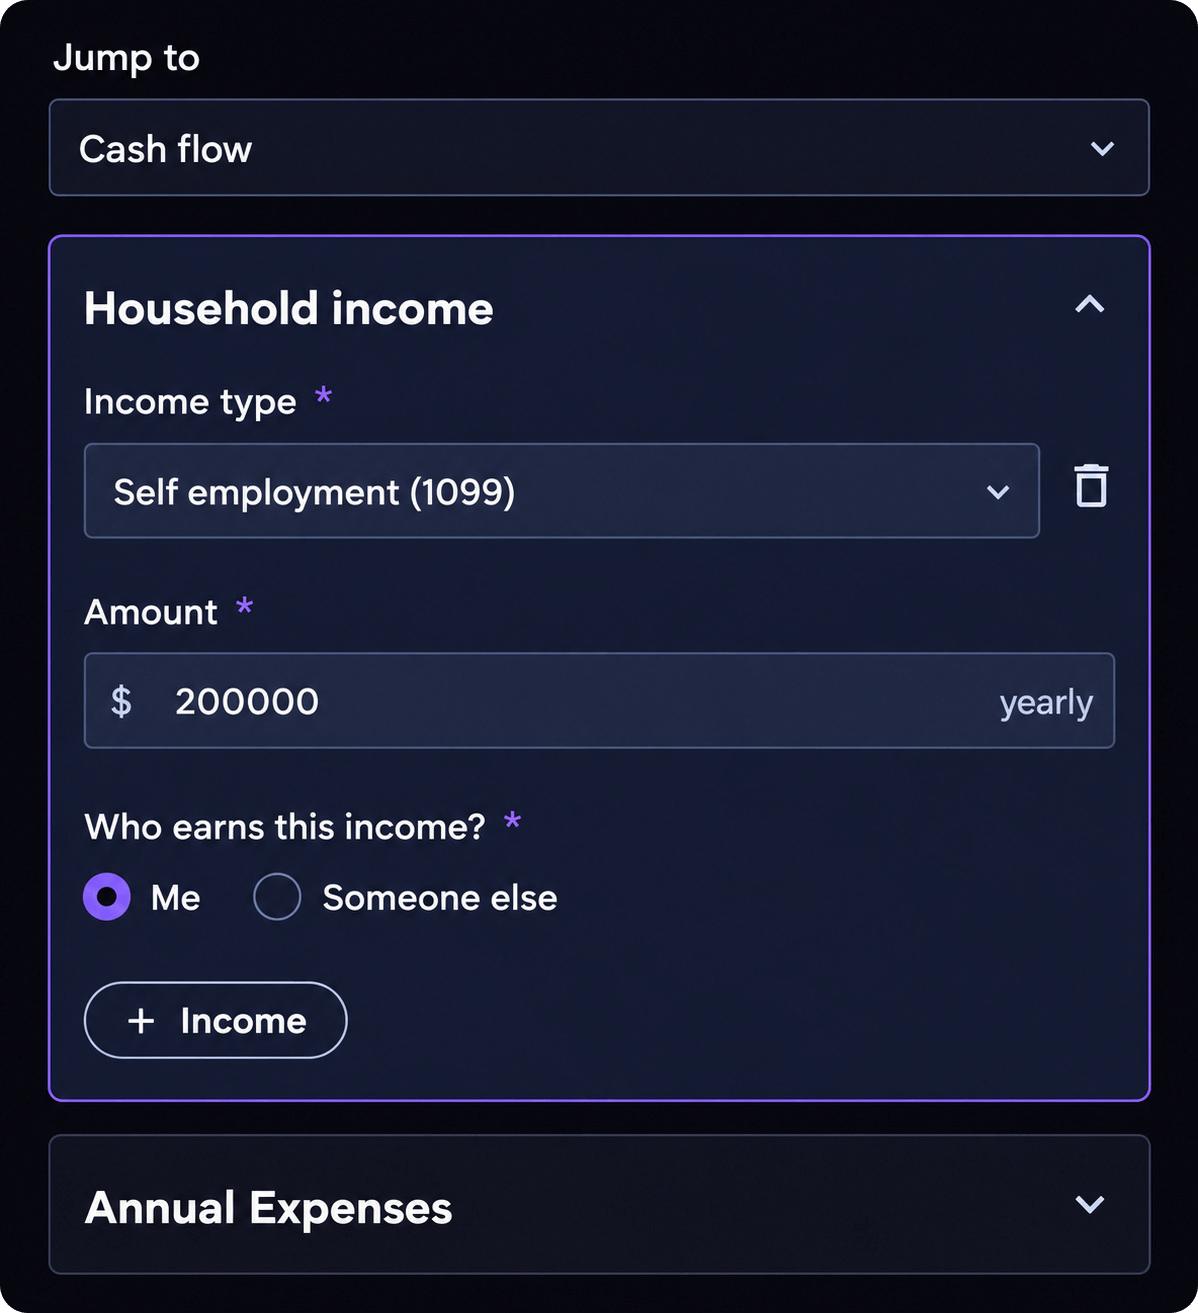
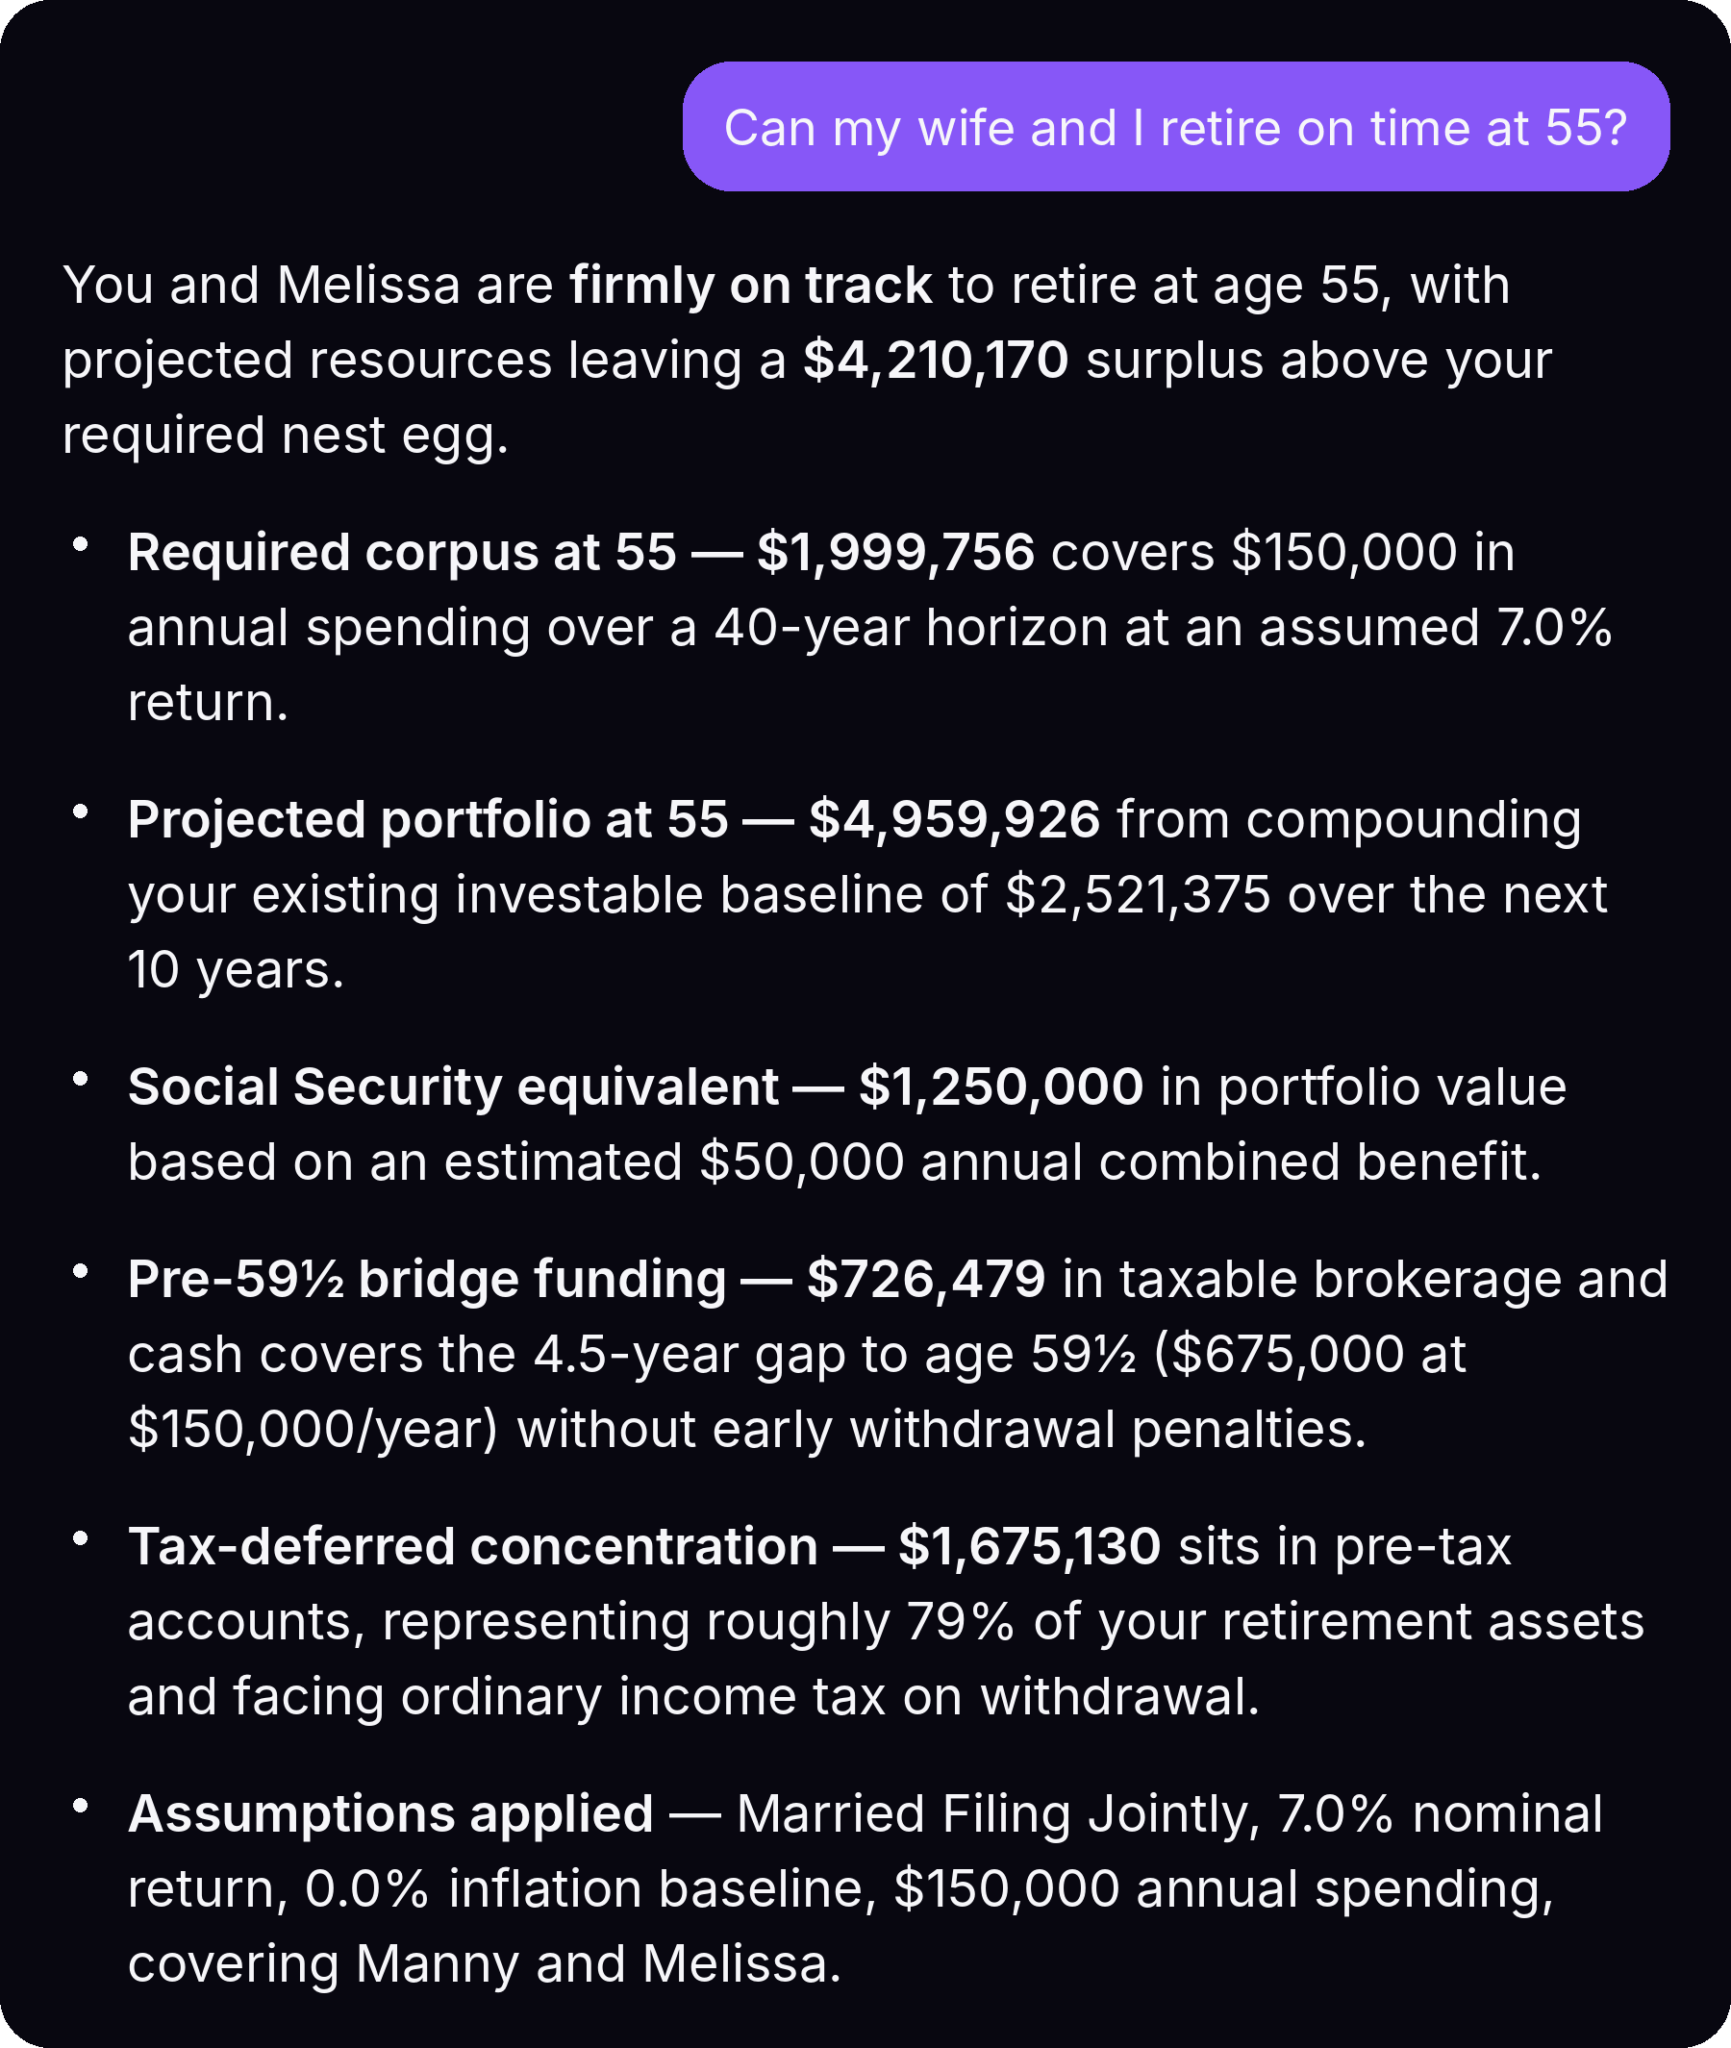
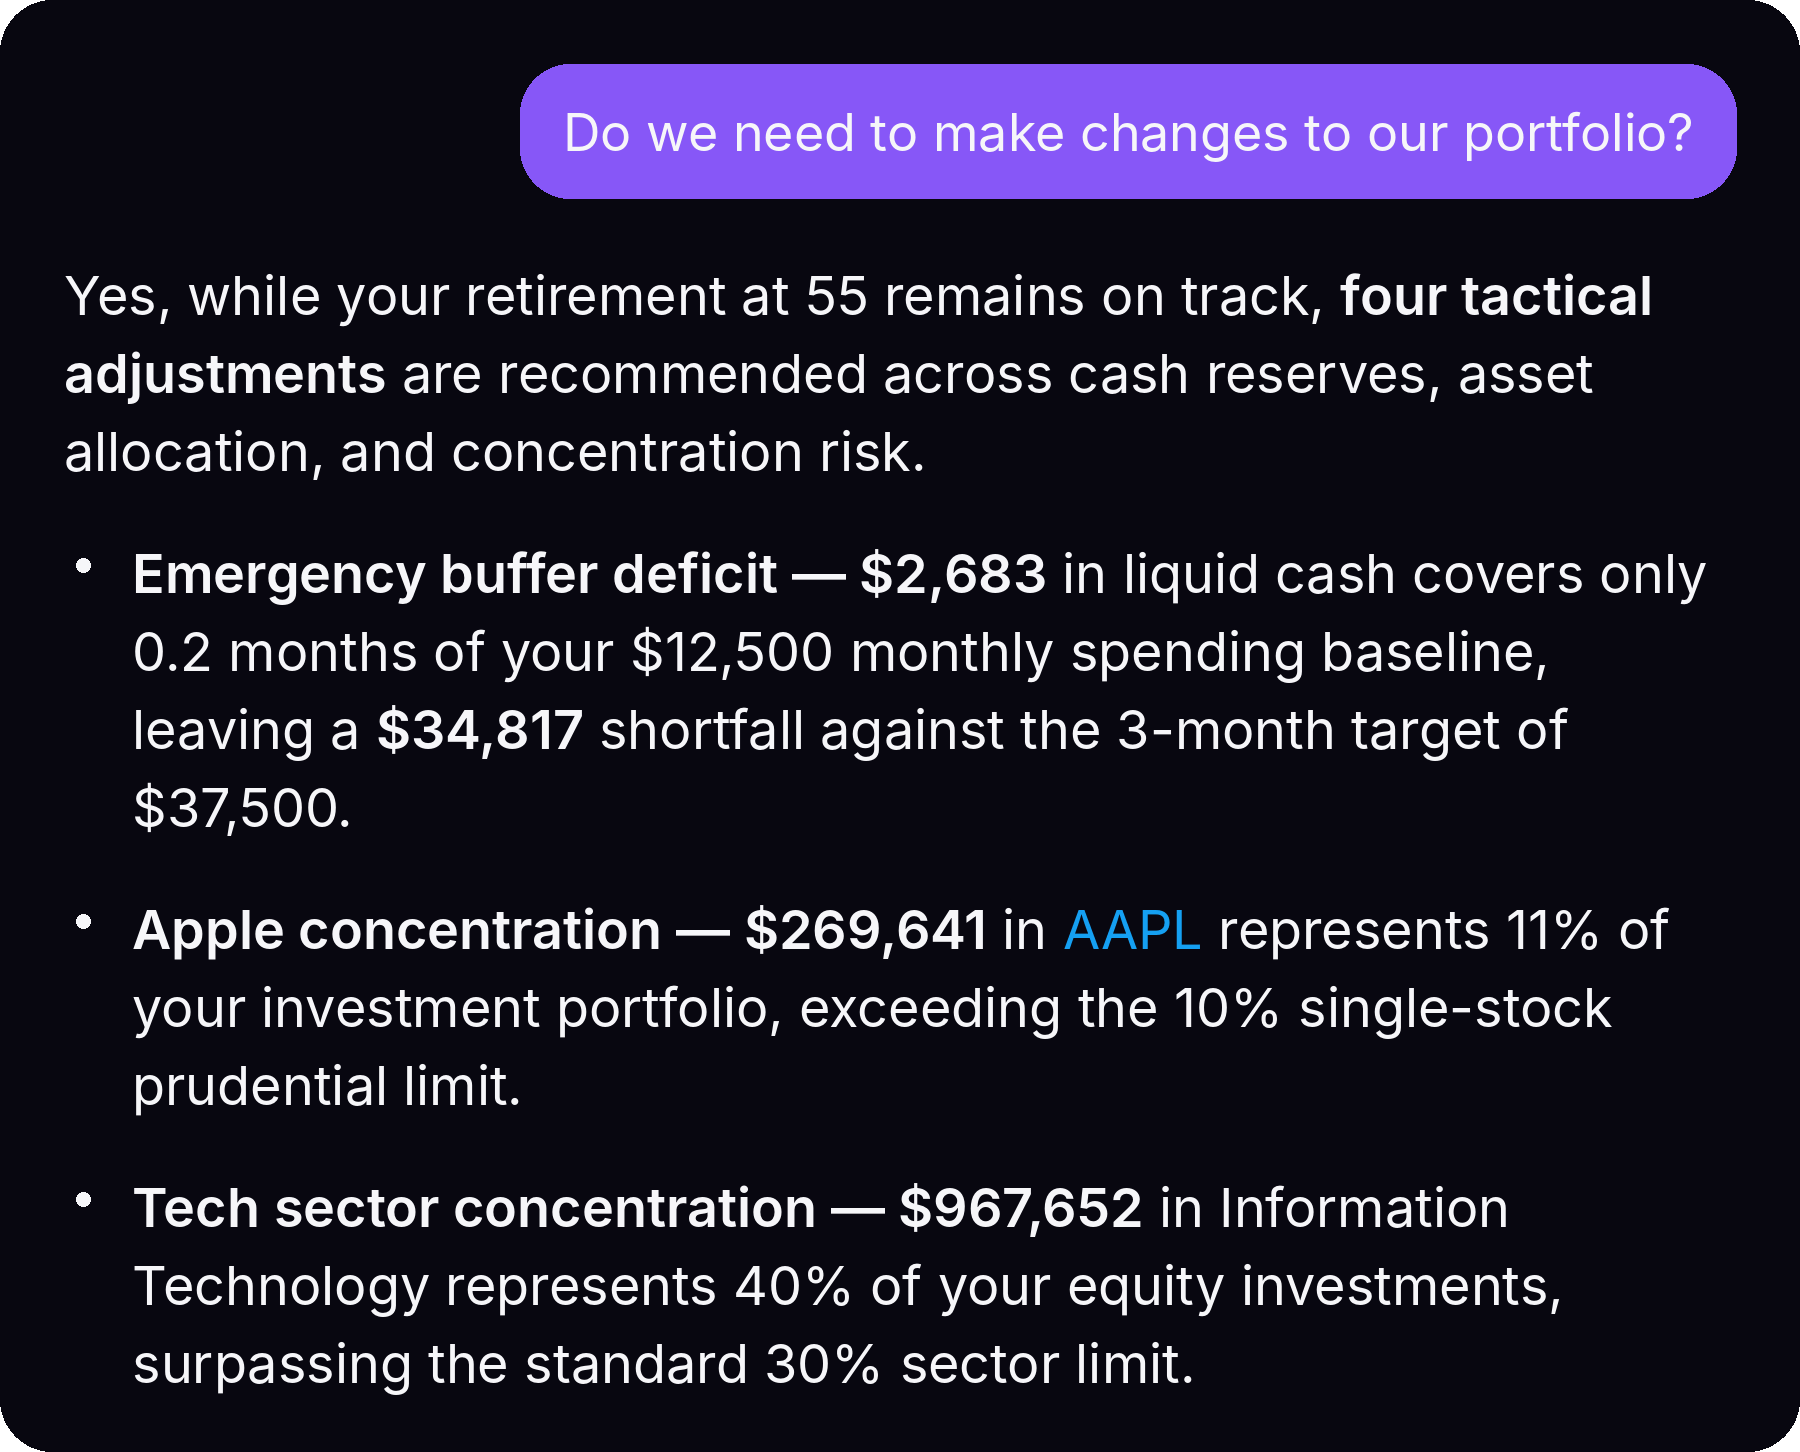
To understand the practical application of Mezzi, consider a hypothetical couple, "Manny and Melissa," both mid-career professionals living in the San Francisco Bay Area. They have two children, private school tuition, a volatile income stream from a tech career, and a desire to retire by age 55.
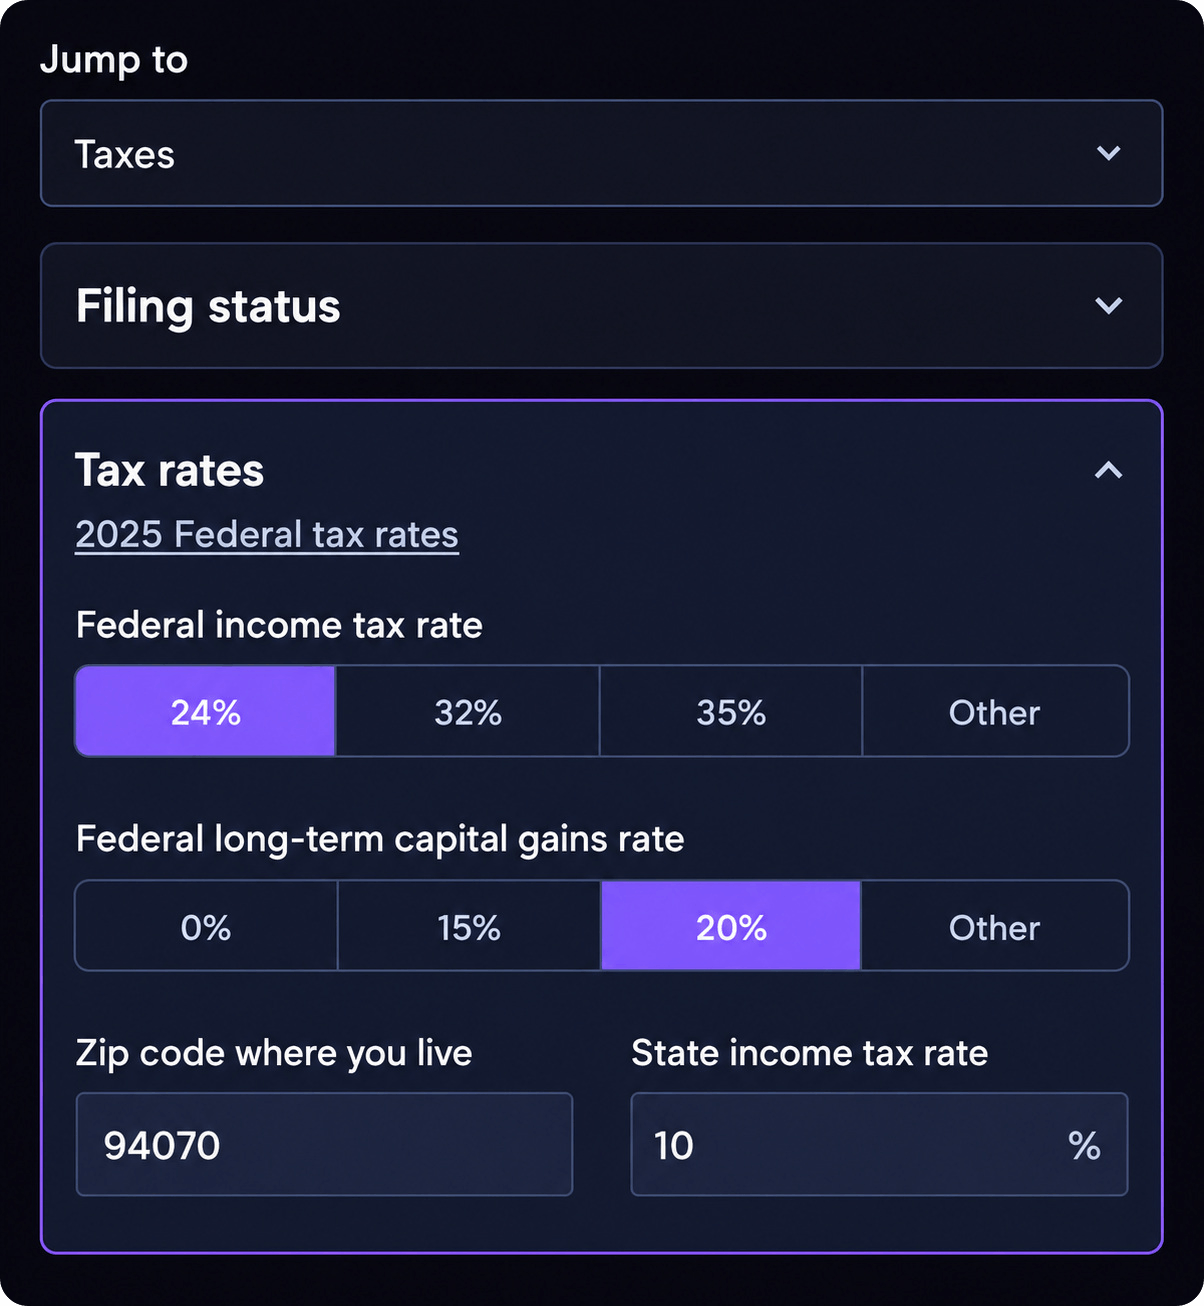
When they input their data into Mezzi, the platform immediately identifies that their retirement goal is tethered to their current tax and investment strategy.
- The Problem: They are over-exposed to their employer’s stock, a common issue for tech workers.
- The Mezzi Solution: The AI suggests a systematic, tax-efficient sell-off plan over the next five years, calculating exactly which tax lots to harvest to offset capital gains.
- The Result: By the time they reach their target retirement age, their portfolio is diversified, their tax burden has been minimized through automated harvesting, and they have a clear understanding of which accounts to draw from first to maintain their lifestyle.
This is the "nuance" that traditional, static planning software misses. Because Mezzi allows for continuous, iterative conversation, the couple can update their goals as their life changes—perhaps deciding to keep a rental property longer than initially planned—and the AI instantly adjusts the financial projections.
Implications: The Democratization of Financial Advice
The most significant implication of the Mezzi model is the democratization of high-level financial strategy. Traditionally, comprehensive wealth management was reserved for those with seven-figure portfolios who could afford the 1% annual management fees of a private wealth manager.
For a household with $1 million in assets, a 1% fee equates to $10,000 annually. In contrast, Mezzi’s "Advisory" membership is a fraction of that cost, offering unlimited access to complex, AI-driven financial analysis.
The Role of "Delegations"
The "Delegation" feature represents a massive leap forward in wealth management. Instead of the user having to remember to check their accounts, they can assign Mezzi to monitor their taxable accounts every Monday morning for tax-loss harvesting opportunities. When the AI finds a position with a significant loss, it emails the user a notification. The user retains total control—they "pull the trigger"—but they no longer have to carry the mental load of constant monitoring.
The Human-AI Hybrid Model
It is critical to note that Mezzi does not currently execute trades. It acts as an advisor, not a broker-dealer. While some may see this as a limitation, many seasoned investors view it as a feature. It ensures that the user remains the final decision-maker. As the founder, Manish Jain, often emphasizes, the goal is to provide the data, the logic, and the recommendations so the user can make the most informed decision possible.
Conclusion: Is It Worth It?
Mezzi is not for everyone. If an investor has a simple three-fund portfolio and is content with a "set it and forget it" strategy, a subscription may be unnecessary. However, for those with multiple accounts, complex tax situations, or those who find themselves spending their weekends buried in spreadsheets, the platform is a game-changer.
The current market for financial services is bifurcated between high-cost, high-touch human advisors and low-cost, low-utility robo-advisors. Mezzi occupies the "sweet spot": high-utility, high-intelligence, and cost-effective.
By leveraging AI, investors are no longer flying blind. They are empowered to ask the "dumb" questions they were too embarrassed to ask a human, perform the "what-if" analyses that would take a human advisor hours to compute, and maintain a level of portfolio oversight that was previously impossible for a solo investor. As the platform continues to evolve, adding more sophisticated features like rental property analysis and international support, it is poised to become an essential tool in the modern investor’s kit.

Disclosure: StockTalk Inc., doing business as Mezzi, is an SEC-registered investment adviser. This article is for informational purposes only and should not be construed as personalized investment advice, a securities recommendation, or an offer of advisory services. SEC registration does not imply any level of skill or training. Past performance is not indicative of future results.

 Muslim
 Rifan Muazin
 Nila Kartika Wati
 Lina Hope
 Asep Darmawan
 Basiran
