
 Rifan Muazin
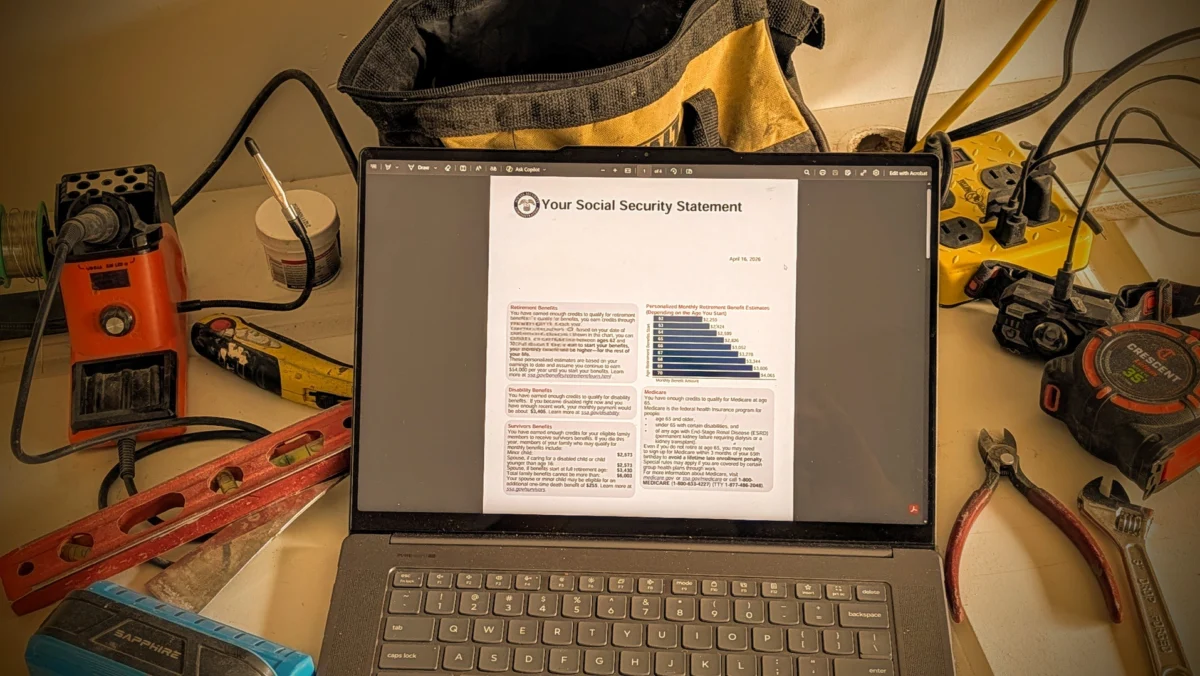
For decades, the financial independence community has operated under a shared assumption: Social Security is a "fuzzy concept" for the distant future—a government promise too far off and too uncertain to include in the serious calculations of someone retiring in their 30s or 40s. While it serves as a critical safety net for millions of traditional retirees, early retirees have historically treated it as a financial phantom.
However, as the movement matures and its earliest pioneers enter their 50s and beyond, the math is shifting. It turns out that Social Security is not just a future safety net; it is a tangible asset that, when correctly valued, can dramatically accelerate the path to financial freedom. By utilizing the concept of Net Present Value (NPV), early retirees can stop ignoring their future benefits and start leveraging them as part of their current net worth.
The Core Concept: Net Present Value (NPV)
To understand why Social Security matters today, we must move past the idea of monthly checks and look at the "Net Present Value" of that future income stream. In financial terms, NPV calculates the value of a series of future cash flows in today’s dollars.

If you are 30 years old, the NPV of your future Social Security is negligible; the compounding power of money you save today far outweighs the distant, inflation-adjusted promise of a government check. But for those in their 40s, 50s, or even early 60s, the picture changes. When you view Social Security as a chunk of capital you already "own" but haven’t accessed yet, you realize it functions as a bond-like asset in your portfolio. It is an inflation-protected, guaranteed income stream that reduces the amount of personal capital you need to hold in traditional investments.
The Chronology of Financial Planning
The Early Decades: The "Zero Value" Phase
For those in their 20s and 30s, the focus is exclusively on building a "stash." Because the benefits are three decades away, the discount rate applied to those future payments renders their present value nearly zero. During this phase, relying on government promises is a strategic error. The focus remains on aggressive saving and index fund investing.
The Mid-Career Pivot: The "Hidden Asset" Phase
As workers move into their 40s and 50s, the time horizon shortens. This is the period where the "slacker incentive" of the Social Security system becomes apparent. Because the system uses your 35 highest-earning years to calculate benefits, the benefit curve is front-loaded. You earn the vast majority of your potential benefit in the first decade or two of work. Consequently, the marginal benefit of working an extra year to "boost" your Social Security payout is often far lower than the benefit of investing that same year’s income independently.

The Pre-Retirement Years: The "Safety Net" Phase
For those nearing age 60, Social Security transitions from a theoretical benefit to a core retirement pillar. By performing an NPV calculation, individuals can determine exactly how much they can reduce their personal savings withdrawal rate. If your expected Social Security payment covers your essential living expenses, your "risk of ruin" drops to nearly zero, regardless of market volatility.
Supporting Data: The Math of Retirement
To illustrate the power of this calculation, consider a 55-year-old individual, whom we will call "Shane." Shane has faced recent financial setbacks and is anxious about his ability to retire. Most traditional advisors would counsel him to work until age 70 to maximize his Social Security benefit.
However, when we calculate the NPV of his potential benefits, we find a counterintuitive truth: the difference in value between retiring at 62 versus 70 is often smaller than anticipated when accounting for the "Time Value of Money." If Shane retires at 62 and invests his payouts, the compounding growth of those funds often outperforms the increase in the monthly check he would receive by waiting until 70.

| Age at Claim | Monthly Benefit (Estimated) | NPV (in today’s dollars) |
|---|---|---|
| 62 | $1,800 | ~$320,000 |
| 67 | $2,500 | ~$310,000 |
| 70 | $3,100 | ~$295,000 |
Note: These figures are illustrative simulations. Individual results vary based on career history and inflation adjustments.
The data shows that waiting longer does not always result in a higher "lifetime value" once you account for the opportunity cost of not having that money to invest during your peak early-retirement years.
Official Perspectives and the "Fairness" Debate
Critics frequently argue that Social Security is a precarious system, susceptible to political shifts and funding gaps. While it is true that the program faces long-term solvency challenges, it remains the most significant political priority for the largest voting bloc in the United States: the aging population.

Official statements from the Social Security Administration (SSA) emphasize that the program is designed as a progressive benefit—replacing a higher percentage of pre-retirement income for low-wage earners than for high-wage earners. For the high-net-worth individual, Social Security may eventually be means-tested or reduced. However, as one veteran retiree noted, "If you are wealthy enough to have your benefits cut, you likely don’t need them to survive anyway." This realization shifts the perspective: treat Social Security as a "bonus" or a "margin of safety" rather than the foundation of your survival.
Implications for Your Strategy
The realization that Social Security has a measurable present value has three major implications for your retirement strategy:
- Reduced Workload: You may be closer to retirement than you think. By adding the NPV of your Social Security to your current net worth, you can lower your required "safe withdrawal rate" from your private investments.
- Increased Flexibility: If your basic expenses are covered by projected Social Security payments, you can afford to take more risks with your remaining portfolio or transition to a "lifestyle career" that focuses on passion rather than peak earnings.
- Correction of the "35-Year Fallacy": Many assume that if they don’t work for 35 years, their benefit will be decimated. Because the formula is progressive and heavily weighted toward early years, you gain the most value by working your first 10-15 years. Every year after that offers diminishing returns.
Conclusion: Taking Control
The era of ignoring Social Security is over. By treating your future benefits as a component of your current balance sheet, you gain a more accurate, and often more optimistic, picture of your financial independence.

Your Homework:
- Create your account: Visit ssa.gov and authenticate via login.gov. This is the single most important step in quantifying your future income.
- Run the numbers: Use an online NPV calculator or an AI tool to estimate the present value of your projected monthly benefit.
- Adjust your plan: Once you see that $100,000 to $400,000 "hidden" asset on your spreadsheet, re-evaluate your target retirement date. You may find that your "freedom day" is significantly closer than you previously believed.
The math of early retirement is not just about how much you save; it is about how accurately you value the promises made to your future self. By bridging the gap between your current savings and your future benefits, you can retire with the confidence that the safety net is already woven into your plan.

 Muslim

 Ammar Sabilarrohman

 Asep Darmawan

 Asro

 Layla Zulfa

 Nila Kartika Wati

