
 Asep Darmawan
By Hannah Wanjie Ryder
October 9, 2026
For decades, the financial architecture of the African continent has been governed by a paradox: nations with burgeoning potential and improving institutional frameworks have been forced to pay exorbitant risk premiums to access global capital markets. This systemic inequity is largely dictated by the "Big Three" credit-rating agencies—Fitch, Moody’s, and S&P—whose standardized methodologies have long been accused of failing to capture the unique nuances of African economies.
However, a transformative shift is underway. The emergence of the Africa Credit Rating Agency (ACRA) signals a potential turning point in how the continent’s sovereign risk is perceived, graded, and priced. By grounding assessments in the lived realities of African markets rather than colonial-era analytical frameworks, the ACRA aims to dismantle the biases that have historically stifled African development.
Main Facts: The Structural Bias in Sovereign Ratings
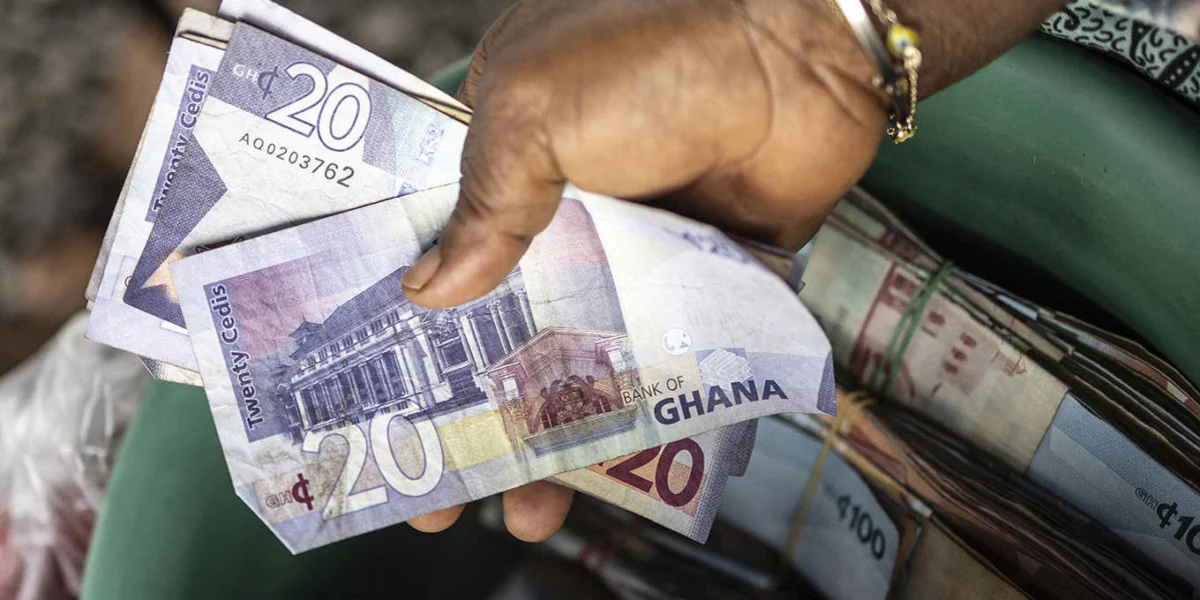
To understand the necessity of the ACRA, one must first recognize the fundamental disconnect between the current global credit system and the reality of African growth. When international agencies evaluate a country like Kenya, Ghana, or Nigeria, they apply a rubric designed for developed Western economies.
Imagine taking a high-stakes university exam and answering every question correctly, only to receive a failing grade because your paper was evaluated against the answer key for a completely different subject. This is the daily reality for African treasuries. The major agencies often prioritize historical data points and rigid fiscal metrics that ignore the structural transformation, digital innovation, and demographic dividends defining modern Africa.
The "Big Three" are not merely observers; they are gatekeepers. Their ratings dictate the interest rates African nations pay on Eurobonds. When these agencies issue a downgrade—often based on subjective "political risk" assessments—the cost of borrowing spikes immediately. This creates a vicious cycle: debt servicing costs rise, fiscal space shrinks, and the very investments needed for development are cannibalized to pay interest to foreign creditors.
Chronology: A History of Marginalization
The struggle for sovereignty in financial assessment is not new. It is the culmination of decades of systemic exclusion.
- 1990s – Early 2000s: As African nations began moving away from concessional aid toward market-based financing, the dominance of the "Big Three" solidified. These agencies expanded their reach, yet their analytical models remained tethered to Western macroeconomic indicators.
- 2008 – 2015: The "Africa Rising" narrative saw a surge in Eurobond issuances. However, the lack of localized, independent credit analysis meant that global markets relied exclusively on the Big Three, leading to volatile pricing that rarely reflected internal growth trajectories.
- 2020 – 2022: The COVID-19 pandemic laid bare the fragility of this system. Despite efforts to maintain fiscal stability, African nations faced rapid downgrades, which choked off liquidity exactly when it was needed most. The discourse around "sovereign debt distress" became a self-fulfilling prophecy facilitated by rating methodologies.
- 2023 – 2025: The African Union (AU) and the African Development Bank (AfDB) intensified calls for a continental credit rating entity. Consultations were held across Nairobi, Addis Ababa, and Johannesburg to define the mandate for an institution that prioritizes local context.
- 2026: The formal rollout of the Africa Credit Rating Agency (ACRA) begins, marking the first time the continent has established a unified, independent mechanism to challenge the status quo.
Supporting Data: The Cost of Miscalculation
The impact of inaccurate credit ratings is not merely theoretical; it is quantifiable in the billions of dollars. According to recent data from the United Nations Economic Commission for Africa (UNECA), African countries pay, on average, a "risk premium" that is significantly higher than that of their peers in Asia or Latin America, even when macroeconomic fundamentals are comparable.
- The Interest Rate Gap: African nations currently pay an average of 5% to 8% more on international bonds than countries with similar debt-to-GDP ratios in other regions.
- Volatility Indicators: Research indicates that African credit ratings are 40% more volatile than those of other emerging markets. This instability makes long-term infrastructure planning nearly impossible for finance ministries.
- Capital Flight: Misleading assessments by major agencies have, in several instances, triggered "herd behavior" among institutional investors, leading to capital flight during periods of temporary liquidity crunch, which further exacerbates the crisis they predicted.
The ACRA’s primary objective is to bridge this "information asymmetry." By providing granular data—such as domestic resource mobilization capacity, agricultural output resilience, and private sector dynamism—the ACRA provides a more accurate picture of a nation’s ability to honor its debts.
Official Responses: Navigating the Global Pushback
The reception of the ACRA has been predictably bifurcated.
From the Continent’s Leadership:
The African Union has championed the agency as a matter of economic decolonization. "We are no longer content to be passive recipients of risk assessments that do not understand our potential," noted an AU spokesperson during the agency’s launch. "The ACRA is about reclaiming our narrative."
From Global Financial Institutions:
The response from the "Big Three" and their traditional institutional partners has been one of cautious skepticism. Spokespeople for Moody’s and S&P have maintained that their methodologies are "globally consistent" and necessary for international investors to compare risks across borders. They argue that "local" agencies may lack the independence required to avoid political capture by domestic governments.
The Counter-Argument:
ACRA proponents argue that the "independence" of the Big Three is a myth, noting their failures during the 2008 global financial crisis, where they provided "AAA" ratings to toxic subprime mortgage assets. The ACRA’s charter includes rigorous, transparent governance protocols, including an independent board of international financial experts, to ensure that ratings remain objective and resistant to political interference.
Implications: A New Era of Sovereign Finance
The successful integration of the ACRA into global financial markets will have profound implications for the continent.
1. Lowering the Cost of Capital
If the ACRA can successfully provide a more nuanced risk assessment, it will effectively narrow the "risk premium" gap. For a country like Ghana or Zambia, a reduction of just 1% in borrowing costs represents hundreds of millions of dollars annually—funds that could be redirected toward education, healthcare, and climate adaptation.
2. Encouraging Intra-African Investment
Currently, capital often flows out of Africa to the West, only to return as expensive debt. By building confidence in local institutions, the ACRA could help foster an environment where African pension funds and insurance companies feel more comfortable investing in the bonds of neighboring countries, effectively creating a more integrated African capital market.
3. Incentivizing Institutional Reform
Because the ACRA focuses on specific institutional strengths, it provides a "roadmap" for African governments. By highlighting the areas that actually matter for long-term growth—such as regulatory transparency, digital infrastructure, and trade connectivity—the agency encourages governments to invest in the reforms that lead to sustainable development, rather than just chasing the arbitrary metrics favored by Western agencies.
4. Challenging the Monopoly of Information
Perhaps the most significant implication is the end of the information monopoly. The ACRA does not seek to replace the Big Three overnight; rather, it seeks to become a mandatory point of reference for any investor interested in the continent. When an investor sees a "B" rating from a major agency alongside an "A-" assessment from the ACRA, they will be forced to ask why there is a discrepancy. That question is the beginning of a more rational, evidence-based approach to African finance.
Conclusion: The Path Forward
The establishment of the Africa Credit Rating Agency is a bold assertion of financial sovereignty. While the road ahead is fraught with challenges—ranging from international skepticism to the need for deep, technical capacity—it is a necessary evolution.
For too long, the narrative of African risk has been defined by outsiders who viewed the continent through a narrow lens of vulnerability. The ACRA offers a different perspective: one that sees the capacity for growth, the power of innovation, and the strength of a continent on the move. By providing a more accurate mirror for its own economies, Africa is finally taking control of the tools that will shape its economic future. The exam hasn’t changed, but the answer key finally reflects the reality of the continent.

 Lina Hope
 Basiran

 Laily UPN

 Iffa Jayyana

 Rifan Muazin

 Suro Senen


 Lina Irawan
