
 Rifan Muazin
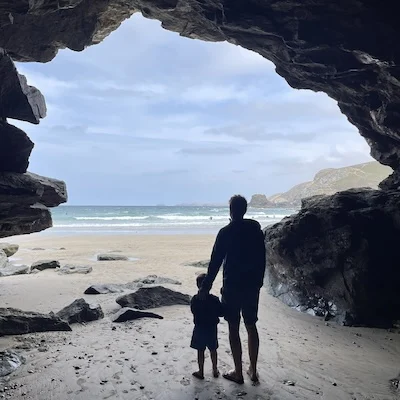
It has been ten years since the host of the popular Financial Independence Podcast walked away from his corporate career, trading a traditional salary for the autonomy of early retirement. A decade later, he finds himself in a position that defies the conventional narrative of the "Financial Independence, Retire Early" (FIRE) movement: he is wealthier than he ever anticipated, yet he is navigating the uncomfortable, uncharted territory of a life without long-term professional goals.
The Evolution of the "Lean" Philosophy
When the podcaster first embarked on his journey, his strategy was rooted in "Lean FIRE"—a minimalist approach characterized by extreme frugality and an exit strategy built on the assumption that he could always return to software development if his finances faltered. However, a decade of market performance and personal growth has shifted his perspective entirely.
"I’m glad that ‘Fat FIRE’ happened accidentally over the years," he notes. "If you’re in a good job that’s high-paying, and you’re not completely miserable, I would suggest sticking with it for a bit longer than you expected. The backup plan of just picking up another software developer job is perhaps not as robust as it was 10 years ago."
This realization is underscored by the rapid advancement of Artificial Intelligence. As a software developer, he once viewed his coding skills as a permanent safety net. Today, he admits that the landscape has shifted so dramatically that he would be "a bit worried" if he were still reliant on a developer’s salary to survive. This professional obsolescence has only deepened his gratitude for the financial buffer he built during his peak earning years.
Chronology of a Financial Transformation
The host’s journey can be categorized into three distinct phases: the accumulation phase, the transition to freedom, and the current "optimization for joy" phase.
- 2014: The initial departure from the workforce. The focus was on extreme efficiency, tax optimization, and hitting the bare-minimum threshold to sustain a modest lifestyle.
- 2015–2020: A period of "deprogramming." The host began to move away from the obsession with efficiency, realizing that many of his previous anxieties about money were rooted in a scarcity mindset.
- 2021–2024: The era of "asset-based lifestyle creep." Rather than fearing spending, he began to embrace the idea that his portfolio could support an "unlimited" lifestyle. During this time, he moved from strict optimization to a philosophy of simplicity, abandoning complex tax maneuvers like backdoor Roth contributions in favor of mental peace.
Supporting Data: The Shift to Asset-Based Spending
A central theme of the host’s reflection is the difference between negative and positive lifestyle creep. Traditionally, lifestyle creep is viewed as a danger—when an individual increases their spending in lockstep with a salary raise, leaving them vulnerable to job loss.
Conversely, the host argues that "asset-based" lifestyle creep is sustainable. Using the 4% rule as a baseline, he illustrates that as a portfolio grows from $1 million to $1.2 million, the individual gains a sustainable $8,000 in annual spending power.
Strategic Portfolio Adjustments
To secure this lifestyle, the host recently made a significant tactical shift in his investment strategy. Recognizing that he had "won the game," he moved approximately 10% of his portfolio into 30-year Treasury Inflation-Protected Securities (TIPS).
"The real yield on these 30-year TIPS is near 3% at the moment," he explains. "They provide a floor of spending for us when we hit our 70s and RMDs [Required Minimum Distributions] start kicking in." By locking in these yields, he has effectively removed the need to micromanage his investments, allowing his "wealth machine" to run on autopilot while he focuses on his family.
Official Insights: The Ramit Sethi Influence
The host credits much of his mental shift to conversations with author and financial expert Ramit Sethi. Two key lessons from Sethi have become cornerstones of the host’s current life:
- "Why spend less when you can spend more?" The host now realizes that his capacity to spend is limited by time and energy, not by his bank account. Consequently, when he does decide to buy something, he opts for the highest quality available, knowing that the item will last longer and provide more utility.
- The acceptance of waste. Previously, the host was obsessed with avoiding sunk costs. Today, he is comfortable cutting trips short if they have lost their luster, prioritizing his immediate well-being over the "efficiency" of completing a pre-planned itinerary.
"Old me would definitely not have done that," he says, referring to a recent trip to Canada where he booked an expensive, last-minute flight home simply because the family felt they had peaked in their enjoyment. "It was the right call. We ended the trip on a high."
Implications for the Future: Seeking "Gravity"
As the host looks toward the next 15 years—which he identifies as his family’s "peak spending years"—he is turning his attention away from portfolio growth and toward the creation of a "home base."
He is currently researching locations on the East Coast of the United States, searching for a place that offers high "gravity." By this, he means a location so rich in community, walkability, and recreational value that it naturally draws his children back as they grow older. This is a move from pure financial management to legacy-building and environmental design.
The Challenge of the "Great Unknown"
Perhaps the most profound takeaway from the last decade is the realization that money, while providing freedom, does not provide purpose.
"This is the first year I can remember in my adult life where I didn’t have some long-term goal driving me on," he admits. "It’s quite uncomfortable, if I’m honest."
For an individual who spent his entire career planning for tomorrow, the shift to "living for today" has been a radical adjustment. Whether it is choosing to play tennis for cardiovascular health—rather than forcing himself to use a rowing machine he despises—the host is now prioritizing the experience of his life over the metrics of it.
Conclusion: A New Horizon
After ten years, the lessons from the Financial Independence Podcast are clear: financial independence is not the destination; it is the starting point for a deeper exploration of how to live well. The host has successfully moved beyond the need to "optimize" his life, finding that true wealth is the ability to spend without guilt, the freedom to value simplicity over complexity, and the courage to exist in the present without a pre-ordained ten-year plan.
As he enters his second decade of freedom, the focus has shifted from "How much do I need to retire?" to "How do I make today as meaningful as possible?" For those currently on the path to financial independence, his message is a gentle reminder: don’t wait for the finish line to start living. If you have built the wealth machine, ensure you are using it to build the memories that matter.

 Nana Wu
 Sagoh

 Raul Delapena Setiawan

 Reynand Wu



 Azzam Bilal Chamdy

 Ali Ikhwan
