
 Nila Kartika Wati
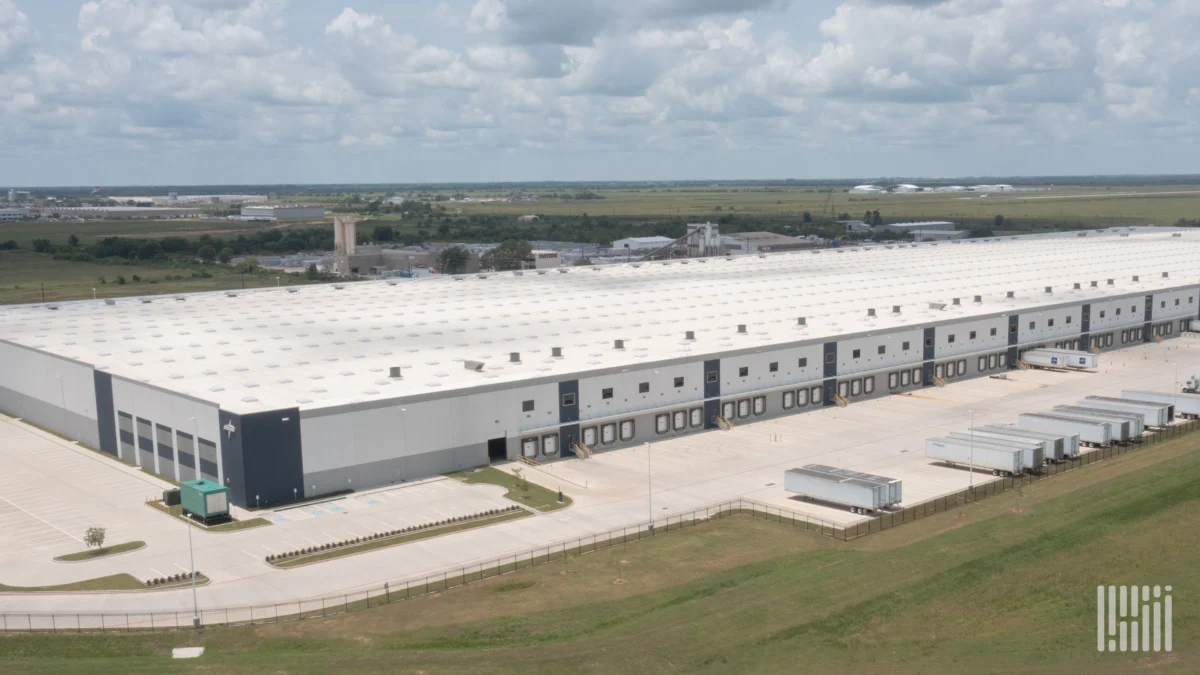
For the past two years, the headlines have been filled with promises of a massive "reshoring boom," painting a picture of a revitalized American industrial landscape that would provide an endless influx of new freight for domestic trucking carriers. However, as the data matures and the hype settles, a more nuanced—and arguably more complex—reality is emerging. For the carrier, the question is no longer whether a generalized manufacturing surge is coming, but rather how to identify the specific pockets of industrial activity that are actually putting goods onto trailers today.
The State of the "Boom": Deconstructing the Data
To understand the current freight landscape, one must first separate political narrative from economic reality. IoT Analytics, which meticulously tracks manufacturing construction spending based on U.S. Census Bureau data, recently published an analysis concluding that characterizing the current climate as a "reshoring boom" is premature.
When stripping away the noise of the computer and electronics sector—which is heavily skewed by semiconductor fabrication plants that require massive capital investment but generate relatively low volumes of traditional truckload freight—the numbers tell a sobering story. Manufacturing construction spending, adjusted for inflation, grew by only about 2.3% between February 2025 and March 2026. Furthermore, manufacturing employment has actually declined by 1% since the implementation of recent, widespread tariff policies, showing only a marginal recovery in the most recent reporting periods.
The Kearney Reshoring Index supports this tempered view. While 2025 showed modest improvements over 2024 regarding domestic production share, the U.S. remains significantly below the levels required to suggest a structural, long-term shift back to domestic manufacturing. Perhaps most telling is the December 2025 survey from the Institute for Supply Management, which revealed that 64% of companies have no plans to reshore, with only 36% actively pursuing or planning such moves.
Chronology of Investment: From Policy to Concrete
The "reshoring" narrative is not entirely false; it is simply geographically and sectorally concentrated. Understanding the timeline of these projects is essential for a carrier’s business development strategy.
- 2023–2024 (The Planning Phase): Federal legislation, including the CHIPS Act and the Infrastructure Investment and Jobs Act, spurred an initial wave of announcements. During this period, the freight was almost exclusively confined to site preparation and early-stage construction.
- 2025 (The Construction Peak): A massive influx of capital hit the ground. Mega-projects, such as Eli Lilly’s $27 billion investment in pharmaceutical manufacturing and various battery facility groundbreakings, defined this period. Freight was dominated by steel, precast concrete, and heavy equipment.
- 2026 (The Transition): We are currently witnessing a shift. Some projects are entering production ramp-up phases, while others—particularly in the EV and semiconductor sectors—are facing headwinds, restructuring, or, in some cases, pauses.
- 2027–2028 (The Operational Horizon): The facilities currently under construction are expected to reach full-scale output. This represents the next significant opportunity for carriers to secure long-term, high-frequency freight contracts.
Key Industry Sectors: Where the Freight Actually Moves
For a carrier, the "reshoring" story is not a rising tide that lifts all boats. Instead, it is a series of specific, actionable opportunities. Carriers must focus on four distinct sectors:
1. Pharmaceutical Manufacturing
This is the "crown jewel" of current reshoring freight. With major commitments from Eli Lilly, Merck, and Johnson & Johnson, pharmaceutical production is moving closer to home. Unlike consumer goods, pharma freight is high-value, compliance-intensive, and relies on strict chain-of-custody protocols. For carriers that have invested in safety records and rigorous documentation, this sector acts as a "moat"—a competitive advantage that prevents less-qualified operators from entering the space.
2. Food and Beverage
Unlike tech or automotive, food cannot be offshored. Supply chain instability has forced manufacturers to prioritize domestic reliability. The opportunity here is not in national, big-box retail lanes, which are dominated by large carriers, but in the "middle tier." Regional dairy cooperatives, specialty food producers, and co-packing facilities require flexible, regional capacity—the perfect niche for small-to-mid-sized fleets.
3. Flatbed and Infrastructure Materials
The federal commitment to infrastructure, combined with the demand for data center construction, is fueling a long-term need for flatbed capacity. Because construction projects operate on strict, time-certain schedules, carriers who can demonstrate reliability in delivering steel and structural components to job sites earn "stickiness" that is rarely found in the volatile spot market.
4. Automotive Regional Supply Chains
While EV-specific production has seen recent volatility, the regional supply chain for internal combustion and hybrid powertrains remains robust. The retooling of major plants—such as the Belvidere facility in Illinois—is creating a constant need for just-in-time component transport. This is high-pressure freight that rewards carriers capable of integrating with EDI systems and meeting stringent delivery windows.
The Semiconductor Exception: Why It Is Not a Target
It is vital for carriers to understand why the semiconductor industry, despite the headlines, is not a viable source for consistent truckload freight. Semiconductor fabrication is about precision, not volume. A facility costing tens of billions of dollars may produce chips that fit into a few shipping containers per week. The "freight" generated by a fab is primarily in the construction phase; once the plant is operational, the output is often moved via air or specialized high-security logistics, offering little for the average regional dry van or flatbed carrier.
Implications for Carrier Strategy: How to Win
The most common mistake carriers make is waiting for a "routing guide" to open up. In the industrial sector, routing guides are rarely finalized during the initial construction of a facility.
The "Before-the-Load" Prospecting Strategy
- Map the Geography: Utilize the Reshoring Initiative’s database (reshorenow.org) to identify facilities within a 300-mile radius of your home terminal.
- Target the Right Personnel: Bypass procurement departments. Focus your outreach on the logistics or transportation managers at the specific facility level. These are the individuals tasked with filling capacity gaps during the critical first 18 months of a plant’s operation.
- Offer Solutions, Not Just Capacity: When approaching a mid-sized food manufacturer or a Tier 2 automotive supplier, present yourself as a partner capable of handling short-notice pickups and consistent, regional inter-plant transfers.
- Leverage Documentation: In sectors like pharma and automotive, your compliance infrastructure is your primary sales tool. Ensure your carrier packet, safety data, and insurance information are professional and ready to send at a moment’s notice.
The Bottom Line
The "reshoring boom" is not a singular event; it is a long-term reconfiguration of the American supply chain. For the trucking industry, the opportunity lies in the regionalization of manufacturing. While national trends are helpful for context, the real money will be made by the carrier who drives the industrial corridors in their own backyard, identifies the mid-sized shippers who are struggling to find reliable service, and builds relationships before the formal routing guides are locked.
The window of opportunity is not closing; it is simply narrowing its focus. Carriers who move away from chasing spot-market headlines and toward building deep, regional partnerships with active manufacturing sites will find that the "reshoring" reality is exactly what they have been waiting for.

 Lina Hope
 Reynand Wu
 Jia Lissa
 Basiran
 Sagoh
