
 Rifan Muazin
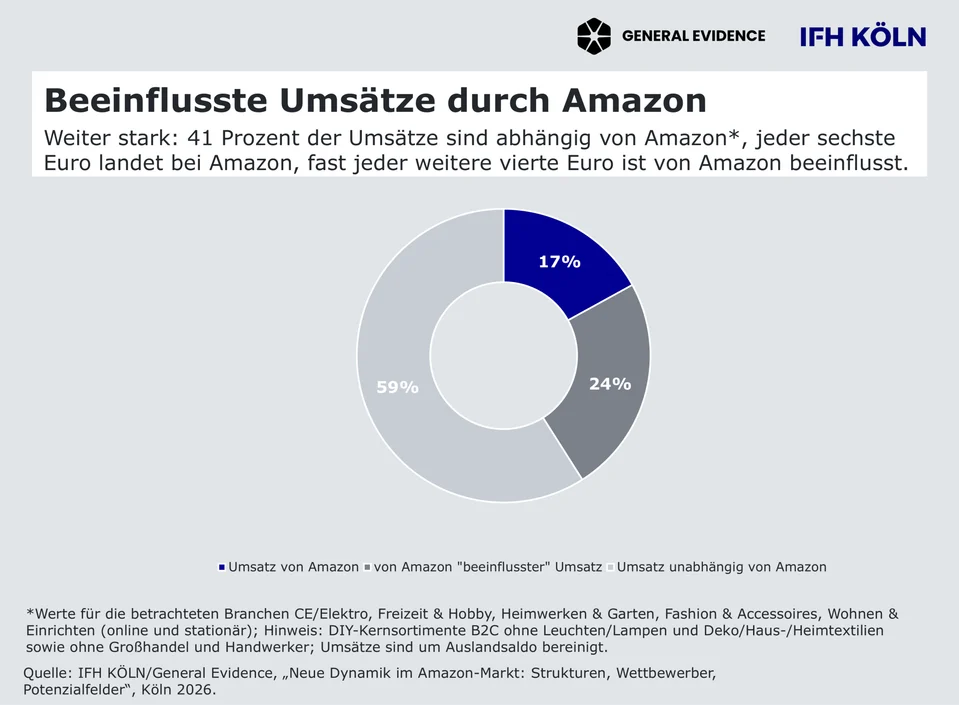
The landscape of German retail is undergoing a structural shift, and at the epicenter of this transformation stands a singular entity: Amazon. A comprehensive new study conducted by the Institut für Handelsforschung (IFH KÖLN) in collaboration with General Evidence has shed light on the sheer scale of Amazon’s footprint in Europe’s largest economy. The findings reveal that Amazon is no longer merely an online marketplace; it has become an indispensable infrastructure layer for the German consumer economy, dictating trends, pricing benchmarks, and logistics standards across the nation.
With a 63% share of the total online retail market, Amazon’s reach is pervasive. The data suggests that for the average German consumer, "shopping online" is almost synonymous with navigating the Amazon interface. However, beneath the headline figures, the report unveils a complex narrative of third-party dominance, intensifying competition from low-cost Chinese rivals, and a profound, lingering impact on the physical high street.
Main Facts: The Anatomy of Market Dominance
The statistics presented by IFH KÖLN are nothing short of staggering. In 2025, sales generated via Amazon in Germany climbed to €69.1 billion, a year-over-year increase of €3.2 billion, or approximately 5%. This growth highlights the company’s resilience in a macroeconomic environment often characterized by fluctuating consumer confidence and inflationary pressures.
The Power of the Marketplace
Crucially, the study identifies that Amazon’s own direct retail operations represent only a fraction of its total influence. Of the 63% total online market share, Amazon’s first-party retail accounts for 17.2%. The vast majority—46.1%—is generated by "Selling Partners." This confirms that Amazon has successfully pivoted from being a merchant to being a landlord of digital real estate, earning significant revenue through fees, logistics services, and advertising while offloading inventory risk to millions of third-party vendors.
The Prime Ecosystem
Customer loyalty remains the bedrock of this success. The survey data indicates that 97% of German online shoppers utilize Amazon at least occasionally. More importantly, 59% of these shoppers are Prime members. This membership model creates a "lock-in" effect, where the convenience of free shipping and integrated services effectively eliminates the friction that might otherwise drive a consumer to explore alternative platforms.
Chronology: Building an Infrastructure of Convenience
Amazon’s rise in Germany was not an overnight phenomenon; it was the result of a decades-long commitment to logistical dominance and consumer trust.
- 1998: Amazon enters the German market by acquiring ABC Bücherdienst, signaling its intent to dominate European book sales.
- Early 2000s: Expansion into consumer electronics, home goods, and media. Amazon establishes its first major distribution hubs, setting a new standard for delivery speeds that legacy German retailers struggle to match.
- 2007: The launch of Amazon Prime in Germany transforms the platform from a marketplace into a service ecosystem. The focus shifts from "price" to "convenience."
- 2010–2020: Rapid scaling of the Marketplace model. By empowering SMEs to sell on the platform, Amazon effectively captures the "long tail" of the German retail economy.
- 2024–2025: Facing inflationary headwinds, Amazon deepens its investment in domestic logistics networks, further distancing itself from traditional retail competitors.
- Present Day: Amazon accounts for 17% of all retail spending in Germany, including physical brick-and-mortar transactions, with a "shadow influence" over an additional 24% of consumer spending.
Supporting Data: Mapping the Digital Landscape
The IFH KÖLN report provides a granular look at the competitive forces currently vying for the German consumer’s wallet.
Table: Market Share and Influence (Key Categories)
| Category | Amazon Direct Share | Marketplace/Partner Share | Total Influence |
|---|---|---|---|
| Online Retail | 17.2% | 46.1% | 63.3% |
| Total Retail (Incl. Offline) | 7.1% | 9.9% | 41.0%* |
*Includes direct sales and influence/discovery impact.
The "Influence" metric is perhaps the most revealing aspect of the study. It suggests that even when a consumer does not complete a purchase on Amazon, they often use the platform for product research, price comparisons, and reading reviews. This "showrooming" effect forces physical retailers to contend with Amazon’s data-driven pricing, even if they never interact with the platform’s checkout page.
Official Responses and Industry Dynamics
While Amazon remains the undisputed king of German e-commerce, the market is not static. The emergence of aggressive international players is beginning to create ripples in what was previously a stable duopoly.
The Rise of Shein and Temu
IFH KÖLN notes that while Amazon added €3.2 billion in sales, Chinese platforms Shein and Temu recorded a combined growth of €1 billion. While this is lower in absolute terms, the growth rate is significant. The report highlights that one in eight German consumers is now shifting at least some of their spending to these platforms.
The primary driver for this migration is price sensitivity. However, the study balances this by noting that in "key performance indicators"—specifically product range, user experience, and delivery reliability—Amazon remains the gold standard. For the average German shopper, Amazon is the "safe" choice, while Temu and Shein are currently relegated to "impulse" or "bargain" shopping.
Domestic Retailers: The Defense
Legacy players like Otto and Zalando are not standing still. The study shows these domestic giants increased their combined sales by €1.4 billion last year. By doubling down on sustainable fashion, curated brand experiences, and localized customer service, these companies are attempting to carve out a "premium" niche that Amazon’s mass-market approach sometimes fails to satisfy.
Implications: A Future Defined by Amazon
The implications of these findings are profound for policymakers, competing retailers, and the German economy at large.
1. The Death of the "Independent" Retailer
As Amazon’s influence touches 41% of all product spending, the barrier to entry for independent retailers is becoming insurmountable. If a business is not on Amazon, it is effectively invisible to a vast segment of the population. This creates a dependency that regulators in Brussels and Berlin are increasingly scrutinizing under antitrust laws.
2. Logistical Dominance as a Barrier
Amazon’s massive investment in its logistics network acts as a "moat." By providing faster, more reliable, and cheaper shipping than any competitor can achieve independently, Amazon has raised the cost of entry for the entire industry. Smaller e-commerce players simply cannot compete on delivery speed without sacrificing margins, creating a two-tier digital economy.
3. The Shift in Consumer Behavior
The fact that 97% of German online shoppers use Amazon suggests a permanent shift in consumer psychology. The expectation of "one-click" ordering, next-day delivery, and hassle-free returns has become the default baseline. Retailers who cannot meet these expectations are being pushed to the periphery.
4. Regulatory Challenges
With such a significant portion of the economy passing through a single platform, the German government faces a dilemma: how to foster innovation and competition without dismantling the logistical efficiency that consumers have come to rely on. The rise of Chinese platforms adds a layer of geopolitical complexity, as these platforms are often viewed through a different regulatory lens regarding labor standards, environmental impact, and data privacy.
Conclusion: A Balancing Act
The study by IFH KÖLN serves as a wake-up call for the European retail sector. Amazon’s dominance is not just a result of clever marketing; it is the outcome of a deeply integrated, highly efficient infrastructure that serves the consumer better than many of its rivals.
However, the growth of Chinese competitors and the resilience of domestic players like Otto and Zalando suggest that the market is not yet a closed loop. The battle for the future of German retail will be fought not just on price, but on the ability to provide a superior, trusted experience. As Amazon continues to exert its influence over both the online and offline worlds, the defining challenge for the next decade will be ensuring that this digital giant remains a platform for growth rather than an insurmountable gatekeeper.
For now, the data is clear: Amazon is the central nervous system of German commerce, and the rest of the industry must adapt to a landscape where the rules are written, managed, and enforced by a single, powerful entity.

 Azzam Bilal Chamdy
 Reynand Wu
 Layla Zulfa
 Nana
 Pevita Pearce
 Iffa Jayyana
